

Northrop Grumman lifts 2026 profit forecast as defense demand drives record backlog

Rising military spending by the U.S. and its allies continues to support major defense contractors amid heightened geopolitical tensions. Northrop Grumman says strong demand for aircraft, missile and defense programs boosts third-quarter sales and profit, while pushing its backlog to a record level.
Highlights
- Northrop Grumman raises its 2026 adjusted profit per share forecast to $29.35–$29.75, citing stronger Q3 performance versus the previous $28.60–$29.10 range.
- Backlog hits a record $109.6 billion as of September 30 after $16.4 billion in new contracts, with quarterly orders reaching 1.5 times billings.
- Quarterly sales rise 7% to $11.12 billion and profit increases about 2% to $1.12 billion, led by 14% growth in Aeronautics Systems and robust demand in Defense Systems.
Quarterly growth and upgraded outlook
As reported by Reuters, Northrop Grumman raises its full-year 2026 adjusted profit per share forecast to between $29.35 and $29.75, up from its prior range of $28.60 to $29.10, after stronger third-quarter performance. The company secures $16.4 billion in new contracts during the quarter, with orders reaching 1.5 times billings. Its backlog rises to a record $109.6 billion as of September 30. Quarterly sales increase 7% from a year earlier to $11.12 billion, while profit rises about 2% to $1.12 billion, or $7.89 per share, from $1.10 billion, or $7.67 per share, a year earlier.Program demand supports defense operations
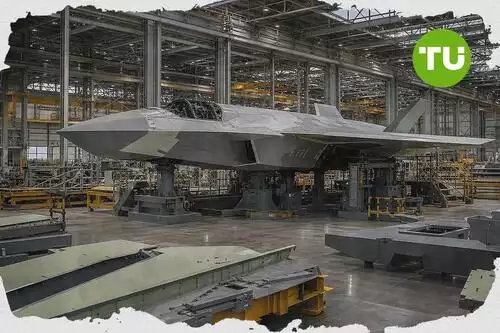
Growth is driven by higher sales across all four business sectors, led by a 14% increase in Aeronautics Systems. That unit benefits from increased B-21 Raider bomber sales, along with higher F-35 production and sustainment work. Sales at the Defense Systems segment rise 12% as the Sentinel missile program continues to ramp up. Demand also remains strong across programs including the F-35, Virginia-class submarines and certain classified programs. Chief Executive Kathy Warden says the company’s record backlog, portfolio positioning and investments support expectations for continued sales and earnings growth, as reflected in its 2027 outlook.In our earlier coverage of the S&P 500’s push toward the 8,000 level, we outlined how investors were looking to third-quarter earnings to justify lofty valuations amid higher oil prices, elevated Treasury yields, and election-related uncertainty. The piece also flagged concentration and market-breadth risks, noting that outsized gains in a narrow group of leaders could leave the broader index vulnerable if results disappoint.
This material may contain third-party opinions, none of the data and information on this webpage constitutes investment advice according to our Disclaimer. While we adhere to strict Editorial Integrity, this post may contain references to products from our partners.
Subscribe to TU news


Did you like the article?




Latest Northrop Grumman Corporation News
Top News


Top 5 companies for you

United States
-
 Afghanistan
-
 Albania
-
 Algeria
-
 Angola
-
 Argentina
-
 Armenia
-
 Australia
-
 Austria
-
 Azerbaijan
-
 Bahamas
-
 Bahrain
-
 Bangladesh
-
 Belarus
-
 Belgium
-
 Bolivia
-
 Botswana
-
 Brazil
-
 Brunei
-
 Bulgaria
-
 Cambodia
-
 Cameroon
-
 Canada
-
 Chile
-
 China
-
 Colombia
-
 Congo
-
 Costa Rica
-
 Cote d'Ivoire
-
 Croatia
-
 Cuba
-
 Cyprus
-
 Czechia
-
 DR Congo
-
 Denmark
-
 Dominican Republic
-
 Ecuador
-
 Egypt
-
 El Salvador
-
 Estonia
-
 Eswatini
-
 Ethiopia
-
 Finland
-
 France
-
 Georgia
-
 Germany
-
 Ghana
-
 Greece
-
 Haiti
-
 Hong Kong
-
 Hungary
-
 India
-
 Indonesia
-
 Iran, Islamic republic
-
 Iraq
-
 Ireland
-
 Israel
-
 Italy
-
 Jamaica
-
 Japan
-
 Jordan
-
 Kazakhstan
-
 Kenya
-
 Korea
-
 Kuwait
-
 Kyrgyzstan
-
 Laos
-
 Latvia
-
 Lebanon
-
 Lesotho
-
 Libya
-
 Lithuania
-
 Luxembourg
-
 Madagascar
-
 Malaysia
-
 Malta
-
 Mauritius
-
 Mexico
-
 Moldova
-
 Mongolia
-
 Montenegro
-
 Morocco
-
 Mozambique
-
 Myanmar
-
 Namibia
-
 Nepal
-
 Netherlands
-
 New Zealand
-
 Nigeria
-
 North Macedonia
-
 Norway
-
 Oman
-
 Pakistan
-
 Palestine
-
 Panama
-
 Papua New Guinea
-
 Paraguay
-
 Peru
-
 Philippines
-
 Poland
-
 Portugal
-
 Puerto Rico
-
 Qatar
-
 Reunion
-
 Romania
-
 Rwanda
-
 Saudi Arabia
-
 Serbia
-
 Singapore
-
 Slovakia
-
 Slovenia
-
 Somalia
-
 South Africa
-
 Spain
-
 Sri Lanka
-
 Sweden
-
 Switzerland
-
 Syria
-
 Taiwan
-
 Tajikistan
-
 Tanzania
-
 Thailand
-
 Trinidad and Tobago
-
 Tunisia
-
 Turkey
-
 UAE
-
 Uganda
-
 Ukraine
-
 United Kingdom
-
United States
-
 Uruguay
-
 Uzbekistan
-
 Venezuela
-
 Vietnam
-
 Yemen
-
 Zambia
-
 Zimbabwe
- Forex
- Crypto










Live News


