

What's behind Booking Holdings's latest 3.8% stock surge?

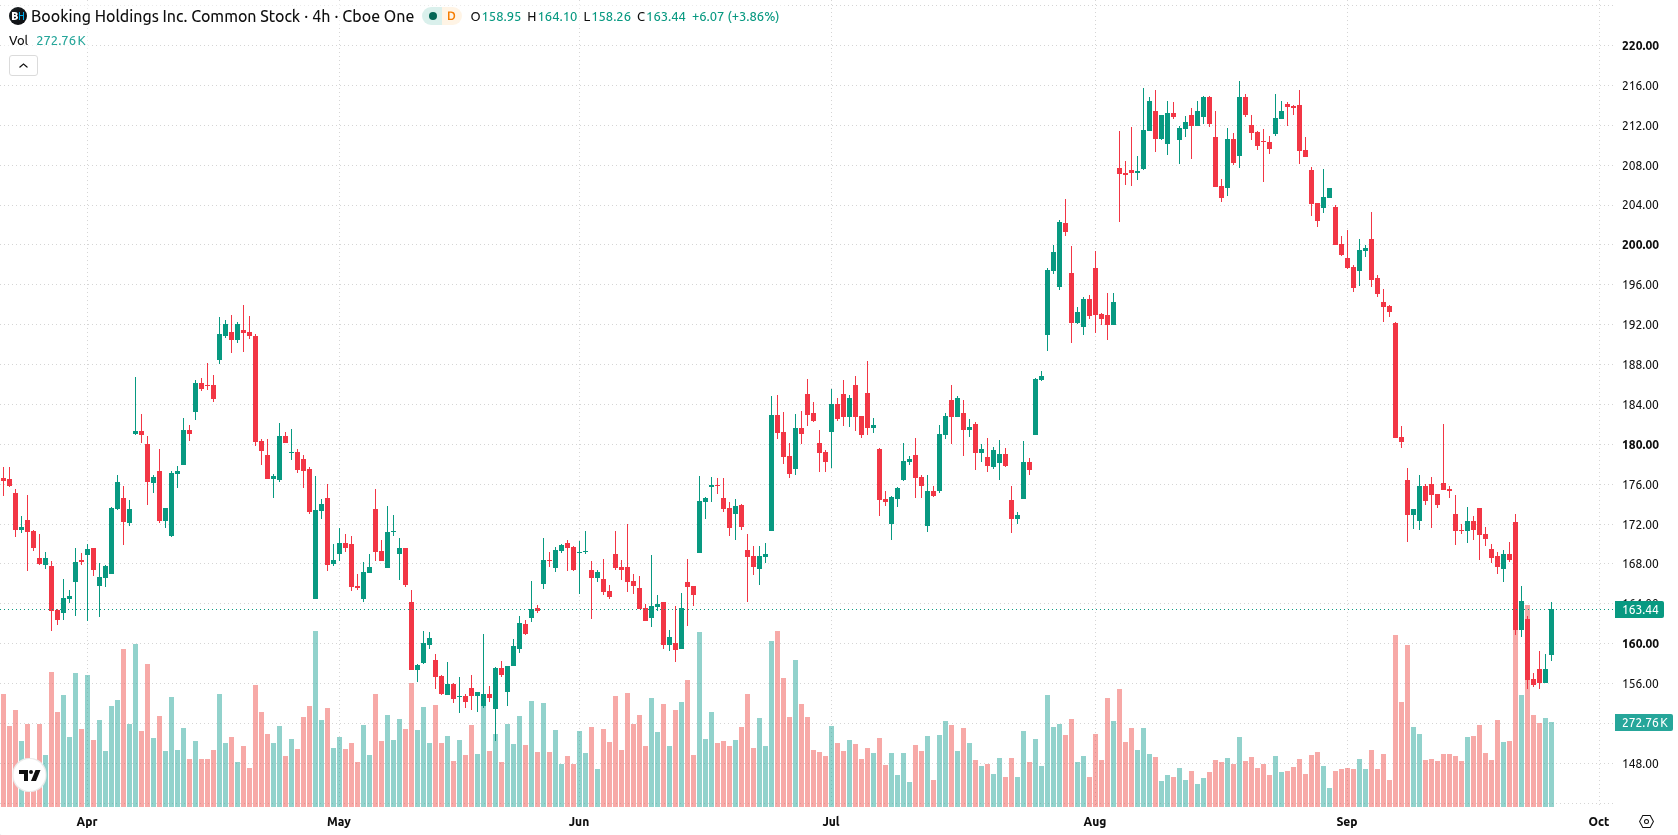
Booking Holdings Inc. (BKNG) surged 3.8% after reporting quarterly adjusted earnings that exceeded consensus expectations, supporting renewed buying interest. The rebound looks limited, with BKNG still trading well below all its major moving averages.
 163.35
165.30
Highlights
- Booking Holdings stock delivered adjusted Q2 2026 EPS of $2.54 on $7.35 billion revenue, exceeding consensus expectations.
- The company forecasts Q3 2026 revenue growth between 4% and 6%, with operating profit margins reaching 35%.
- Shares trade below major moving averages as technical signals show persistent selling, with a predicted price range of $154.88 to $171.91 over the next five sessions.
Revenue outlook and margin gains boost profit sentiment
Booking Holdings Inc. reported adjusted earnings per share of $2.54 for Q2 2026, topping the consensus estimate of $2.43, and recorded revenue of $7.35 billion. The company projected Q3 2026 revenue growth between 4% and 6%. Operating profit margins reached 35% of sales during the period.
Persisting selling pressure as oversold signals counter bullish structure
BKNG is trading well below the 20-day ($179.76), 50-day ($191.66), and 200-day ($184.12) moving averages, a pattern that signals selling pressure across short-, medium-, and long-term timeframes. Immediate resistance is at $171.91, with initial support at $159.25, and longer-term technical structure remains bullish based on the 50-day average holding above the 200-day. Momentum indicators such as MACD and ADX project continued selling, while the RSI, Stochastic RSI, and CCI all indicate the stock is oversold. Bull/Bear Power is negative, showing sellers control intraday moves, and the Awesome Oscillator confirms the bearish momentum. Intraday volatility is elevated at 2.49%, with the stock rebounding near the day's high following an opening downside gap, though underlying momentum remains weak even after today's bounce.
Earlier, analysts noted that Booking Holdings faced persistent downside momentum and technical weakness following regulatory setbacks to its growth strategy. The latest earnings-driven price rebound adds a new dimension but does not alter the prevailing risk, with traders advised to monitor the $154.88 support as a trigger for further downside.






Latest Booking Holdings News


-
 Afghanistan
-
 Albania
-
 Algeria
-
 Angola
-
 Argentina
-
 Armenia
-
 Australia
-
 Austria
-
 Azerbaijan
-
 Bahamas
-
 Bahrain
-
 Bangladesh
-
 Belarus
-
 Belgium
-
 Bolivia
-
 Botswana
-
 Brazil
-
 Brunei
-
 Bulgaria
-
 Cambodia
-
 Cameroon
-
 Canada
-
 Chile
-
 China
-
 Colombia
-
 Congo
-
 Costa Rica
-
 Cote d'Ivoire
-
 Croatia
-
 Cuba
-
 Cyprus
-
 Czechia
-
 DR Congo
-
 Denmark
-
 Dominican Republic
-
 Ecuador
-
 Egypt
-
 El Salvador
-
 Estonia
-
 Eswatini
-
 Ethiopia
-
 Finland
-
 France
-
 Georgia
-
 Germany
-
 Ghana
-
 Greece
-
 Haiti
-
 Hong Kong
-
 Hungary
-
 India
-
 Indonesia
-
 Iran, Islamic republic
-
 Iraq
-
 Ireland
-
 Israel
-
 Italy
-
 Jamaica
-
 Japan
-
 Jordan
-
 Kazakhstan
-
 Kenya
-
 Korea
-
 Kuwait
-
 Kyrgyzstan
-
 Laos
-
 Latvia
-
 Lebanon
-
 Lesotho
-
 Libya
-
 Lithuania
-
 Luxembourg
-
 Madagascar
-
 Malaysia
-
 Malta
-
 Mauritius
-
 Mexico
-
 Moldova
-
 Mongolia
-
 Montenegro
-
 Morocco
-
 Mozambique
-
 Myanmar
-
 Namibia
-
 Nepal
-
 Netherlands
-
 New Zealand
-
 Nigeria
-
 North Macedonia
-
 Norway
-
 Oman
-
 Pakistan
-
 Palestine
-
 Panama
-
 Papua New Guinea
-
 Paraguay
-
 Peru
-
 Philippines
-
 Poland
-
 Portugal
-
 Puerto Rico
-
 Qatar
-
 Reunion
-
 Romania
-
 Rwanda
-
 Saudi Arabia
-
 Serbia
-
 Singapore
-
 Slovakia
-
 Slovenia
-
 Somalia
-
 South Africa
-
 Spain
-
 Sri Lanka
-
 Sweden
-
 Switzerland
-
 Syria
-
 Taiwan
-
 Tajikistan
-
 Tanzania
-
 Thailand
-
 Trinidad and Tobago
-
 Tunisia
-
 Turkey
-
 UAE
-
 Uganda
-
 Ukraine
-
 United Kingdom
-
United States
-
 Uruguay
-
 Uzbekistan
-
 Venezuela
-
 Vietnam
-
 Yemen
-
 Zambia
-
 Zimbabwe
- Forex
- Crypto












