


US Natural Gas ended trading on August 20 down by approximately 3%, while the September NYMEX contract fell toward $2.73/MMBtu after reaching a nearly four-week high the previous day. The main restraining factor remains supply: according to LSEG estimates, average production in the Lower 48 reached a record 111.4 Bcf/d in August, compared with the previous monthly high of 110.7 Bcf/d in July.

At the same time, the weather factor remains moderately positive for demand. Meteorologists expect predominantly above-normal temperatures through the beginning of September, although LSEG forecasts total demand, including exports, to decline from 114.8 Bcf/d this week to 112.9 Bcf/d next week.
Storage surplus continues to narrow
The latest EIA report was noticeably more positive for prices than the previous one. For the week ended August 14, inventories increased by only 16 Bcf after rising by 36 Bcf a week earlier. For comparison, the five-year average build for this week is 29 Bcf. Total gas in storage reached 3.169 Tcf, which is 28 Bcf below last year’s level, but still 185 Bcf, or approximately 6.2%, above the five-year average.
Thus, summer heat and high power burn are gradually reducing the storage surplus, although the market does not yet view this process as a sign of a deficit. The EIA still expects around 3.985 Tcf of gas in storage by the end of October, which would be the highest pre-winter level in roughly a decade.
LNG exports offset record production
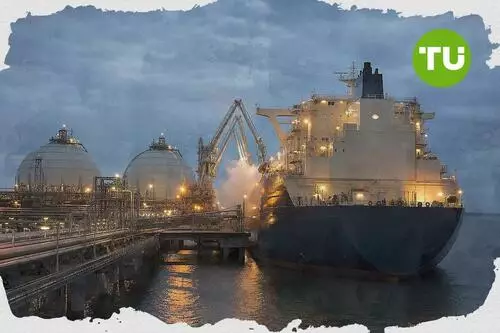
LNG exports remain the main counterbalance to record production. Gas flows to the nine largest U.S. LNG terminals are averaging around 17.2 Bcf/d in August, virtually unchanged from July and slightly below the record 17.4 Bcf/d reached in June. The EIA expects LNG exports to average around 16.5 Bcf/d in the third quarter, while maintenance at Freeport LNG has slightly reduced the previous forecast.
At the same time, the August STEO projects an average Henry Hub price of only around $2.87/MMBtu in the third quarter due to the combination of high production and sufficient inventories. The EIA also forecasts that marketed natural gas production in the U.S. will reach a record 122.5 Bcf/d in 2026, compared with 118.5 Bcf/d in 2025.
Middle East risks keep bullish potential alive
The situation in the Middle East continues to create a potentially strong bullish risk, primarily through the global LNG market. The Strait of Hormuz remains significantly restricted for shipping after the prolonged U.S.-Iran conflict, while on August 18 the Iranian side stated that the full reopening of the strait would depend on the U.S. meeting the terms of the temporary agreement.
As long as NATGAS trades above $2.72-2.70, the chances of renewed growth will remain, but for this to happen. as I warned in the article Natural gas remains under pressure ahead of EIA storage data, bulls still need to break through resistance around $2.82-2.84. Until then, prices may continue to consolidate within the current range.






Latest Natural Gas News


-
 Afghanistan
-
 Albania
-
 Algeria
-
 Angola
-
 Argentina
-
 Armenia
-
 Australia
-
 Austria
-
 Azerbaijan
-
 Bahamas
-
 Bahrain
-
 Bangladesh
-
 Belarus
-
 Belgium
-
 Bolivia
-
 Botswana
-
 Brazil
-
 Brunei
-
 Bulgaria
-
 Cambodia
-
 Cameroon
-
 Canada
-
 Chile
-
 China
-
 Colombia
-
 Congo
-
 Costa Rica
-
 Cote d'Ivoire
-
 Croatia
-
 Cuba
-
 Cyprus
-
 Czechia
-
 DR Congo
-
 Denmark
-
 Dominican Republic
-
 Ecuador
-
 Egypt
-
 El Salvador
-
 Estonia
-
 Eswatini
-
 Ethiopia
-
 Finland
-
 France
-
 Georgia
-
 Germany
-
 Ghana
-
 Greece
-
 Haiti
-
 Hong Kong
-
 Hungary
-
 India
-
 Indonesia
-
 Iran, Islamic republic
-
 Iraq
-
 Ireland
-
 Israel
-
 Italy
-
 Jamaica
-
 Japan
-
 Jordan
-
 Kazakhstan
-
 Kenya
-
 Korea
-
 Kuwait
-
 Kyrgyzstan
-
 Laos
-
 Latvia
-
 Lebanon
-
 Lesotho
-
 Libya
-
 Lithuania
-
 Luxembourg
-
 Madagascar
-
 Malaysia
-
 Malta
-
 Mauritius
-
 Mexico
-
 Moldova
-
 Mongolia
-
 Montenegro
-
 Morocco
-
 Mozambique
-
 Myanmar
-
 Namibia
-
 Nepal
-
 Netherlands
-
 New Zealand
-
 Nigeria
-
 North Macedonia
-
 Norway
-
 Oman
-
 Pakistan
-
 Palestine
-
 Panama
-
 Papua New Guinea
-
 Paraguay
-
 Peru
-
 Philippines
-
 Poland
-
 Portugal
-
 Puerto Rico
-
 Qatar
-
 Reunion
-
 Romania
-
 Rwanda
-
 Saudi Arabia
-
 Serbia
-
 Singapore
-
 Slovakia
-
 Slovenia
-
 Somalia
-
 South Africa
-
 Spain
-
 Sri Lanka
-
 Sweden
-
 Switzerland
-
 Syria
-
 Taiwan
-
 Tajikistan
-
 Tanzania
-
 Thailand
-
 Trinidad and Tobago
-
 Tunisia
-
 Turkey
-
 UAE
-
 Uganda
-
 Ukraine
-
 United Kingdom
-
United States
-
 Uruguay
-
 Uzbekistan
-
 Venezuela
-
 Vietnam
-
 Yemen
-
 Zambia
-
 Zimbabwe
- Forex
- Crypto












