

WTI tests $103 as Middle East tensions fuel supply concerns

WTI is trading around $102.70 per barrel on October 23, continuing its recovery from the October low near $89.00. On the hourly chart, a sequence of higher highs and higher lows remains intact, while prices are holding firmly above the main moving averages.

The recovery is taking place amid ongoing disruptions to oil supplies from the Middle East, so the technical structure remains predominantly bullish, although proximity to resistance increases the likelihood of short-term profit-taking.
Hormuz disruptions sustain geopolitical risk premium
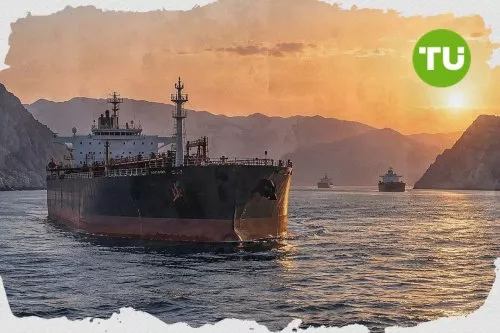
The main factor supporting the oil market has been another escalation of tensions in the Strait of Hormuz. On October 22, reports emerged of attacks on seven oil tankers, allegedly linked to Iranian forces and naval mines. At the same time, the U.S. is increasing its military presence in the region by deploying an additional aircraft carrier group, raising concerns about the resumption of large-scale military operations.
Despite the continuation of maritime transportation through protected corridors, market participants have to account for higher insurance and freight costs, as well as the use of alternative routes. According to Kpler estimates, shipments through the Strait of Hormuz stand at around 12.65 million barrels per day, compared with 17.15 million before the conflict began, indicating continued export restrictions. Meanwhile, Saudi Arabia has increased the capacity of pipelines bypassing the strait to 7 million barrels per day. These measures partially offset the disruptions but do not eliminate the threat of further supply interruptions, so the geopolitical risk premium continues to support high prices.
U.S. inventory declines contrast with weaker demand forecasts
Additional support for oil prices comes from the latest EIA data. The report published on October 21 showed a decline in U.S. commercial crude oil inventories of 3.06 million barrels for the week ending October 16, to 412.5 million barrels, while analysts had expected a decline of just 0.34 million. Gasoline inventories fell by 2.95 million barrels to 205.3 million, indicating that domestic demand remains relatively strong.
At the same time, distillate inventories unexpectedly increased by 1.68 million barrels, although the market had expected a decline of approximately 1.24 million. Refineries operated at 93.4% capacity utilization, processing around 16.6 million barrels per day. Despite mixed trends in petroleum product inventories, the much larger-than-expected decline in crude oil stocks confirms the relative tightness of the U.S. supply-demand balance. The next EIA report is scheduled for October 28 and will be an important indicator for assessing the sustainability of WTI's current recovery.
However, long-term forecasts remain considerably more cautious than current price movements. In its October report, the IEA forecasts a decline in global oil demand of approximately 2.6 million barrels per day in 2026 compared with the previous year, primarily due to high fuel prices and deteriorating economic conditions. In the fourth quarter, the decline in demand could reach 2.5 million barrels per day, with diesel accounting for approximately a quarter of the reduction.
Despite this, the agency notes that global supply recovered to 102.3 million barrels per day in September thanks to increased production by Persian Gulf countries. The EIA, for its part, estimates that global oil inventories declined by approximately 1.9 million barrels per day in the third quarter and forecasts a further decline of 0.7 million in the fourth quarter. At the same time, the agency expects a gradual normalization of supplies in 2027 and a decline in the average Brent price to approximately $87 in the second quarter and $74 by the end of next year. Thus, current high prices largely reflect a temporary shortage of available supplies and geopolitical risks, while a recovery in supply amid weak demand could significantly change the market balance.
Weekend escalation risks put $105 resistance in focus
In the near term, the situation in the Middle East will remain the main source of uncertainty, where even a limited disruption to oil infrastructure could trigger another price spike. At the same time, the recovery of exports through alternative routes and signs of weakening global demand could limit further gains.
At this stage, WTI prices are testing resistance around $103.00, a break above which would support a rise toward strong resistance at $104.00–105.00, where WTI, as I noted in WTI climbs amid Middle East tensions and declining U.S. inventories, could come under some pressure. If active U.S. military operations against Iran resume over the weekend, the market could open on Monday either near the upper boundary of this area or above it. If the U.S. refrains from a military strike, this could provide a reason for profit-taking on long positions.






Latest WTI News


-
 Afghanistan
-
 Albania
-
 Algeria
-
 Angola
-
 Argentina
-
 Armenia
-
 Australia
-
 Austria
-
 Azerbaijan
-
 Bahamas
-
 Bahrain
-
 Bangladesh
-
 Belarus
-
 Belgium
-
 Bolivia
-
 Botswana
-
 Brazil
-
 Brunei
-
 Bulgaria
-
 Cambodia
-
 Cameroon
-
 Canada
-
 Chile
-
 China
-
 Colombia
-
 Congo
-
 Costa Rica
-
 Cote d'Ivoire
-
 Croatia
-
 Cuba
-
 Cyprus
-
 Czechia
-
 DR Congo
-
 Denmark
-
 Dominican Republic
-
 Ecuador
-
 Egypt
-
 El Salvador
-
 Estonia
-
 Eswatini
-
 Ethiopia
-
 Finland
-
 France
-
 Georgia
-
 Germany
-
 Ghana
-
 Greece
-
 Haiti
-
 Hong Kong
-
 Hungary
-
 India
-
 Indonesia
-
 Iran, Islamic republic
-
 Iraq
-
 Ireland
-
 Israel
-
 Italy
-
 Jamaica
-
 Japan
-
 Jordan
-
 Kazakhstan
-
 Kenya
-
 Korea
-
 Kuwait
-
 Kyrgyzstan
-
 Laos
-
 Latvia
-
 Lebanon
-
 Lesotho
-
 Libya
-
 Lithuania
-
 Luxembourg
-
 Madagascar
-
 Malaysia
-
 Malta
-
 Mauritius
-
 Mexico
-
 Moldova
-
 Mongolia
-
 Montenegro
-
 Morocco
-
 Mozambique
-
 Myanmar
-
 Namibia
-
 Nepal
-
 Netherlands
-
 New Zealand
-
 Nigeria
-
 North Macedonia
-
 Norway
-
 Oman
-
 Pakistan
-
 Palestine
-
 Panama
-
 Papua New Guinea
-
 Paraguay
-
 Peru
-
 Philippines
-
 Poland
-
 Portugal
-
 Puerto Rico
-
 Qatar
-
 Reunion
-
 Romania
-
 Rwanda
-
 Saudi Arabia
-
 Serbia
-
 Singapore
-
 Slovakia
-
 Slovenia
-
 Somalia
-
 South Africa
-
 Spain
-
 Sri Lanka
-
 Sweden
-
 Switzerland
-
 Syria
-
 Taiwan
-
 Tajikistan
-
 Tanzania
-
 Thailand
-
 Trinidad and Tobago
-
 Tunisia
-
 Turkey
-
 UAE
-
 Uganda
-
 Ukraine
-
 United Kingdom
-
United States
-
 Uruguay
-
 Uzbekistan
-
 Venezuela
-
 Vietnam
-
 Yemen
-
 Zambia
-
 Zimbabwe
- Forex
- Crypto












