

What's behind TELUS's latest 12.7% stock pullback?

TELUS Corporation (T) fell 12.67% on the announcement of a significant dividend cut and ongoing restructuring efforts, leading to heavy selling pressure. The move is supported by the stock trading well below its major moving averages, underscoring a firmly bearish technical structure.
 13.80
13.91
Highlights
- TELUS cut its quarterly dividend by approximately 55%, reducing the annualized payout to CAD 0.75 per share to prioritize debt reduction.
- The company posted a Q2 2026 net loss, saw declining revenue, and plans non-core asset sales under its new strategy.
- TELUS trades under sustained selling pressure with a bearish technical outlook; expected range is C$11.5–C$13.76 over the next five days.
Dividend reduction and asset sales as company targets debt reduction
TELUS announced a roughly 55% reduction to its quarterly dividend, lowering the annualized payout to CAD 0.75 per share. This adjustment is expected to free up around CAD 2.7 billion by 2028 for debt reduction. The company reported a net loss for the second quarter of 2026, with revenue declines, increased restructuring costs, and plans to sell non-core assets as part of its new corporate strategy.
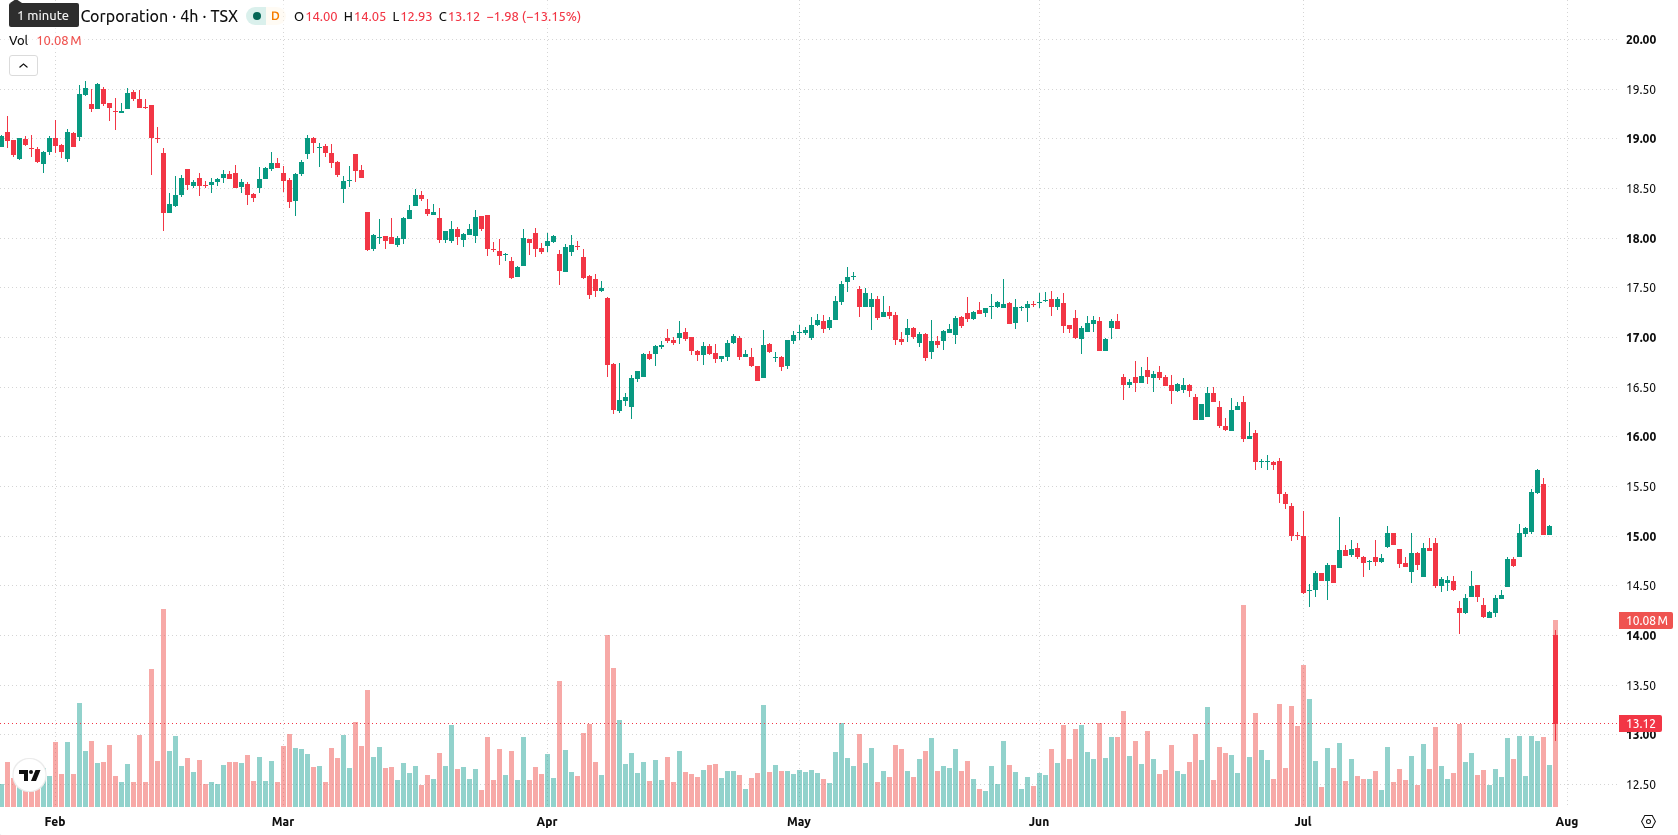
Bearish trend strengthens as technical signals confirm heavy selling
TELUS is currently trading well below its 20-, 50-, and 200-day moving averages (C$14.72, C$15.84, and C$17.83), indicating sustained selling pressure across all timeframes. The medium- and long-term trend remains bearish, with nearest resistance at C$13.76 and support at C$13.02. Momentum signals are mixed: MACD shows a strong sell, ADX points to continued trend strength, and RSI sits just below neutral with a sell bias. Stochastic RSI is high but indicates a strong sell, while CCI and Bull/Bear Power both indicate overbought conditions on recent rebounds. Buyers dominate intraday, but overbought CCI and BBP readings suggest caution. The Awesome Oscillator is neutral.
Previously it was reported that TELUS was showing early signs of recovery potential despite ongoing selling pressure and mixed technical momentum. The current environment marks a notable shift, with dividend cuts and accelerating restructuring firmly entrenching a bearish outlook, making downside risk toward C$11.5 the primary scenario to monitor.








-
 Afghanistan
-
 Albania
-
 Algeria
-
 Angola
-
 Argentina
-
 Armenia
-
 Australia
-
 Austria
-
 Azerbaijan
-
 Bahamas
-
 Bahrain
-
 Bangladesh
-
 Belarus
-
 Belgium
-
 Bolivia
-
 Botswana
-
 Brazil
-
 Brunei
-
 Bulgaria
-
 Cambodia
-
 Cameroon
-
 Canada
-
 Chile
-
 China
-
 Colombia
-
 Congo
-
 Costa Rica
-
 Cote d'Ivoire
-
 Croatia
-
 Cuba
-
 Cyprus
-
 Czechia
-
 DR Congo
-
 Denmark
-
 Dominican Republic
-
 Ecuador
-
 Egypt
-
 El Salvador
-
 Estonia
-
 Eswatini
-
 Ethiopia
-
 Finland
-
 France
-
 Georgia
-
 Germany
-
 Ghana
-
 Greece
-
 Haiti
-
 Hong Kong
-
 Hungary
-
 India
-
 Indonesia
-
 Iran, Islamic republic
-
 Iraq
-
 Ireland
-
 Israel
-
 Italy
-
 Jamaica
-
 Japan
-
 Jordan
-
 Kazakhstan
-
 Kenya
-
 Korea
-
 Kuwait
-
 Kyrgyzstan
-
 Laos
-
 Latvia
-
 Lebanon
-
 Lesotho
-
 Libya
-
 Lithuania
-
 Luxembourg
-
 Madagascar
-
 Malaysia
-
 Malta
-
 Mauritius
-
 Mexico
-
 Moldova
-
 Mongolia
-
 Montenegro
-
 Morocco
-
 Mozambique
-
 Myanmar
-
 Namibia
-
 Nepal
-
 Netherlands
-
 New Zealand
-
 Nigeria
-
 North Macedonia
-
 Norway
-
 Oman
-
 Pakistan
-
 Palestine
-
 Panama
-
 Papua New Guinea
-
 Paraguay
-
 Peru
-
 Philippines
-
 Poland
-
 Portugal
-
 Puerto Rico
-
 Qatar
-
 Reunion
-
 Romania
-
 Rwanda
-
 Saudi Arabia
-
 Serbia
-
 Singapore
-
 Slovakia
-
 Slovenia
-
 Somalia
-
 South Africa
-
 Spain
-
 Sri Lanka
-
 Sweden
-
 Switzerland
-
 Syria
-
 Taiwan
-
 Tajikistan
-
 Tanzania
-
 Thailand
-
 Trinidad and Tobago
-
 Tunisia
-
 Turkey
-
 UAE
-
 Uganda
-
 Ukraine
-
 United Kingdom
-
United States
-
 Uruguay
-
 Uzbekistan
-
 Venezuela
-
 Vietnam
-
 Yemen
-
 Zambia
-
 Zimbabwe
- Forex
- Crypto












