

Oil market reprices long-term supply risk as Iran war keeps futures elevated

Eight months into the Iran war, oil traders are increasingly pricing in a longer period of elevated energy costs rather than a short-lived supply shock. Brent futures for late 2026 and 2027 have climbed sharply, signalling broader concern that disruption in the Gulf and fuel shortages could prolong global inflation pressures.
Highlights
- December 2027 Brent crude futures have surged over 13% since September to $86 a barrel, signaling persistent long-term supply concerns despite IEA forecasts.
- Elevated Gulf transport costs—now nearly one-third of a barrel’s price versus 3% pre-conflict—reflect increased military, insurance, and logistics expenses amid escalating regional attacks.
- European diesel futures hit a record $1,480 per metric ton in September as Middle East conflict and Russian supply disruptions tighten global diesel markets and fuel inflation risk.
Futures markets reflect deeper supply concerns
As reported by Reuters, long-dated Brent contracts are rising even as many industry forecasts still point to a supply recovery next year, highlighting growing scepticism that expected output gains will fully materialise or last. December 2027 Brent crude futures have climbed more than 13% since the start of September to $86 a barrel, the highest level for that contract, while December 2026 contracts are up about 12%.The shift suggests refiners, airlines, commodity traders and asset managers are willing to lock in higher prices well beyond the immediate conflict period. That stands in contrast to projections from the International Energy Agency, which expects global oil supply to rise to 108.3 million barrels per day in 2027 from 100.7 million bpd this year, while demand increases to 104.4 million bpd from 102.4 million bpd.
Even with those projected balances implying a sizeable surplus next year, the rise in long-dated futures indicates investors increasingly doubt that recovering exports and production can restore durable stability. Market attention remains fixed on the Strait of Hormuz, where oil flows have rebounded close to pre-war levels in recent weeks with help from U.S. naval support, but where attacks on vessels and threats of further disruption continue.
Diesel tightness adds to inflation risks
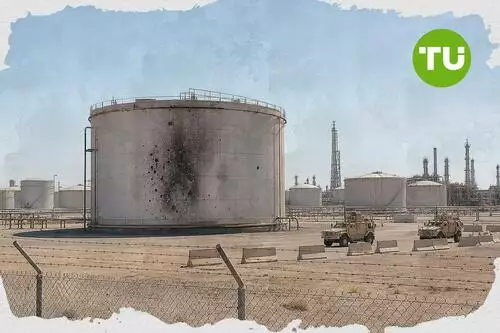
The conflict is also broadening beyond crude flows, with Yemen's Iran-aligned Houthis stepping up missile and drone attacks on Saudi Arabia, including strikes this week on Aramco's headquarters in Dhahran. As a result, the cost of moving oil out of the Gulf has risen sharply, with logistics, freight, insurance and military protection now accounting for nearly a third of transport costs for a barrel of oil from the region, compared with 3% before the war.Pressure is even more acute in diesel markets. Benchmark European diesel futures reached a record $1,480 per metric ton in mid-September, or about $210 per barrel, as disruptions in the Middle East and Russia deepen supply shortages.
Additional strain comes from damage to Russian refining capacity after drone attacks linked to the war in Ukraine. Although U.S. President Donald Trump announces an agreement with Russian President Vladimir Putin to allow some diesel exports to resume and later proclaims an energy ceasefire between Russia and Ukraine, traders remain focused on the limited scale of those exports and the lack of confidence in any ceasefire holding.
That matters for a wider range of industries because diesel fuels trucks, ships, factories and farms across the global economy. With U.S. headline inflation at 3.7% in September and core inflation edging higher, persistent fuel tightness is reinforcing concerns that energy costs may remain structurally higher even if direct fighting eventually eases.
In our earlier article on the surge in oil shipping costs, we explained how conflict-related attacks and rerouting through hotspots like the Strait of Hormuz and the Red Sea pushed tanker and insurance rates to record levels, making freight a much larger share of the delivered crude price. We also noted that these higher transport costs can quickly filter into gasoline and broader consumer prices, particularly in import-dependent markets, and may stay elevated while security risks persist.





Latest Brent News


-
 Afghanistan
-
 Albania
-
 Algeria
-
 Angola
-
 Argentina
-
 Armenia
-
 Australia
-
 Austria
-
 Azerbaijan
-
 Bahamas
-
 Bahrain
-
 Bangladesh
-
 Belarus
-
 Belgium
-
 Bolivia
-
 Botswana
-
 Brazil
-
 Brunei
-
 Bulgaria
-
 Cambodia
-
 Cameroon
-
 Canada
-
 Chile
-
 China
-
 Colombia
-
 Congo
-
 Costa Rica
-
 Cote d'Ivoire
-
 Croatia
-
 Cuba
-
 Cyprus
-
 Czechia
-
 DR Congo
-
 Denmark
-
 Dominican Republic
-
 Ecuador
-
 Egypt
-
 El Salvador
-
 Estonia
-
 Eswatini
-
 Ethiopia
-
 Finland
-
 France
-
 Georgia
-
 Germany
-
 Ghana
-
 Greece
-
 Haiti
-
 Hong Kong
-
 Hungary
-
 India
-
 Indonesia
-
 Iran, Islamic republic
-
 Iraq
-
 Ireland
-
 Israel
-
 Italy
-
 Jamaica
-
 Japan
-
 Jordan
-
 Kazakhstan
-
 Kenya
-
 Korea
-
 Kuwait
-
 Kyrgyzstan
-
 Laos
-
 Latvia
-
 Lebanon
-
 Lesotho
-
 Libya
-
 Lithuania
-
 Luxembourg
-
 Madagascar
-
 Malaysia
-
 Malta
-
 Mauritius
-
 Mexico
-
 Moldova
-
 Mongolia
-
 Montenegro
-
 Morocco
-
 Mozambique
-
 Myanmar
-
 Namibia
-
 Nepal
-
 Netherlands
-
 New Zealand
-
 Nigeria
-
 North Macedonia
-
 Norway
-
 Oman
-
 Pakistan
-
 Palestine
-
 Panama
-
 Papua New Guinea
-
 Paraguay
-
 Peru
-
 Philippines
-
 Poland
-
 Portugal
-
 Puerto Rico
-
 Qatar
-
 Reunion
-
 Romania
-
 Rwanda
-
 Saudi Arabia
-
 Serbia
-
 Singapore
-
 Slovakia
-
 Slovenia
-
 Somalia
-
 South Africa
-
 Spain
-
 Sri Lanka
-
 Sweden
-
 Switzerland
-
 Syria
-
 Taiwan
-
 Tajikistan
-
 Tanzania
-
 Thailand
-
 Trinidad and Tobago
-
 Tunisia
-
 Turkey
-
 UAE
-
 Uganda
-
 Ukraine
-
 United Kingdom
-
United States
-
 Uruguay
-
 Uzbekistan
-
 Venezuela
-
 Vietnam
-
 Yemen
-
 Zambia
-
 Zimbabwe
- Forex
- Crypto












