

Reliance Industries seen posting profit rise as refining and Jio support quarterly earnings

Reliance Industries is expected to deliver a sharp increase in quarterly profit as stronger performance in oil-to-chemicals and digital services offsets continued weakness in retail. The earnings are due after a week in which Jio Platforms made its market debut, giving investors their first view of the telecom and digital unit's results as a listed business.
Highlights
- Analysts expect Reliance Industries' consolidated net profit to rise 17.5% year-on-year to 213.48 billion rupees, with revenue up 28% for the September quarter.
- Record refining margins, higher utilisation, and lower-cost U.S. ethane are set to support a forecasted 47% surge in oil-to-chemicals operating profit, while Jio telecom benefits from an extra day.
- Retail profit is expected to fall 3% due to ongoing margin pressure, and Reliance shares are down 26% year-to-date despite strong oil-to-chemicals performance and Jio's high-profile listing.
Quarterly outlook driven by refining and telecom
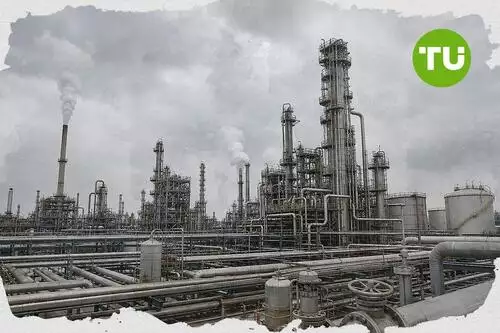
As reported by Reuters, analysts expect Reliance's consolidated net profit for the quarter ended September to rise 17.5% from a year earlier to 213.48 billion rupees, while revenue increases 28%, based on LSEG-compiled estimates.Reliance, which operates the world's largest refining complex in western India, is benefiting from stronger crude-linked dynamics after Brent rises about 60% since the U.S.-Israeli war with Iran breaks out at the end of February. Oil-to-chemicals contributes more than half of the company's revenue, keeping refinery performance central to the quarter's outcome.
Bineet Banka, an analyst at Nomura, says record refining margins and higher refinery utilisation should support oil-to-chemicals profitability, while telecom earnings also benefit from an extra day in the quarter. Kotak Institutional Equities says operating profit in oil-to-chemicals could surge 47%, helped by strong refinery earnings, lower-cost U.S. ethane feedstock and a weaker rupee.
Analysts led by Sanjay Mookim at J.P.Morgan say refining and petrochemicals margins remain strong, while solar commissioning could offer a near-term catalyst.
Retail pressure and valuation concerns remain in focus
Retail is likely to remain a weaker area for the group as margin pressure persists. Motilal Oswal expects Jio EBITDA to rise 2.8%, but forecasts retail profit to fall 3% because of lower-margin quick-commerce deliveries.The earnings release also arrives as investors reassess Reliance's broader valuation after Jio Platforms' blockbuster listing, which makes it India's second-most valuable listed company. The results are set to provide the first detailed indication of how the telecom-to-digital arm is performing after its trading debut.
Reliance shares are down 0.3% at 1,163.4 rupees as of 11:35 IST, extending a 26% decline so far this year, compared with a 12% fall in the Nifty 50. J.P.Morgan says investors have largely looked past stronger oil-to-chemicals margins as they remain concerned about retail valuation pressure, a holding company discount and uncertainty over whether renewable energy investments will create meaningful near-term value.
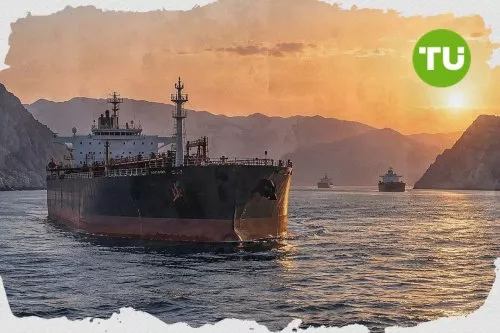
Conflict-driven tanker rate spikes have become a major new component of oil pricing, with freight and insurance surging on disrupted routes through chokepoints such as the Strait of Hormuz and the Red Sea. Our earlier article noted that these higher transport costs can feed into pump prices and squeeze import-dependent markets and Asian refiners’ margins, even as they boost earnings for tanker owners. The piece also highlighted that the shift toward longer, costlier, risk-avoiding routes could persist as companies diversify supply chains away from key chokepoints.






Latest Brent News


-
 Afghanistan
-
 Albania
-
 Algeria
-
 Angola
-
 Argentina
-
 Armenia
-
 Australia
-
 Austria
-
 Azerbaijan
-
 Bahamas
-
 Bahrain
-
 Bangladesh
-
 Belarus
-
 Belgium
-
 Bolivia
-
 Botswana
-
 Brazil
-
 Brunei
-
 Bulgaria
-
 Cambodia
-
 Cameroon
-
 Canada
-
 Chile
-
 China
-
 Colombia
-
 Congo
-
 Costa Rica
-
 Cote d'Ivoire
-
 Croatia
-
 Cuba
-
 Cyprus
-
 Czechia
-
 DR Congo
-
 Denmark
-
 Dominican Republic
-
 Ecuador
-
 Egypt
-
 El Salvador
-
 Estonia
-
 Eswatini
-
 Ethiopia
-
 Finland
-
 France
-
 Georgia
-
 Germany
-
 Ghana
-
 Greece
-
 Haiti
-
 Hong Kong
-
 Hungary
-
 India
-
 Indonesia
-
 Iran, Islamic republic
-
 Iraq
-
 Ireland
-
 Israel
-
 Italy
-
 Jamaica
-
 Japan
-
 Jordan
-
 Kazakhstan
-
 Kenya
-
 Korea
-
 Kuwait
-
 Kyrgyzstan
-
 Laos
-
 Latvia
-
 Lebanon
-
 Lesotho
-
 Libya
-
 Lithuania
-
 Luxembourg
-
 Madagascar
-
 Malaysia
-
 Malta
-
 Mauritius
-
 Mexico
-
 Moldova
-
 Mongolia
-
 Montenegro
-
 Morocco
-
 Mozambique
-
 Myanmar
-
 Namibia
-
 Nepal
-
 Netherlands
-
 New Zealand
-
 Nigeria
-
 North Macedonia
-
 Norway
-
 Oman
-
 Pakistan
-
 Palestine
-
 Panama
-
 Papua New Guinea
-
 Paraguay
-
 Peru
-
 Philippines
-
 Poland
-
 Portugal
-
 Puerto Rico
-
 Qatar
-
 Reunion
-
 Romania
-
 Rwanda
-
 Saudi Arabia
-
 Serbia
-
 Singapore
-
 Slovakia
-
 Slovenia
-
 Somalia
-
 South Africa
-
 Spain
-
 Sri Lanka
-
 Sweden
-
 Switzerland
-
 Syria
-
 Taiwan
-
 Tajikistan
-
 Tanzania
-
 Thailand
-
 Trinidad and Tobago
-
 Tunisia
-
 Turkey
-
 UAE
-
 Uganda
-
 Ukraine
-
 United Kingdom
-
United States
-
 Uruguay
-
 Uzbekistan
-
 Venezuela
-
 Vietnam
-
 Yemen
-
 Zambia
-
 Zimbabwe
- Forex
- Crypto












