

Jacksonville Aviation Authority revenue bonds win AA rating from KBRA
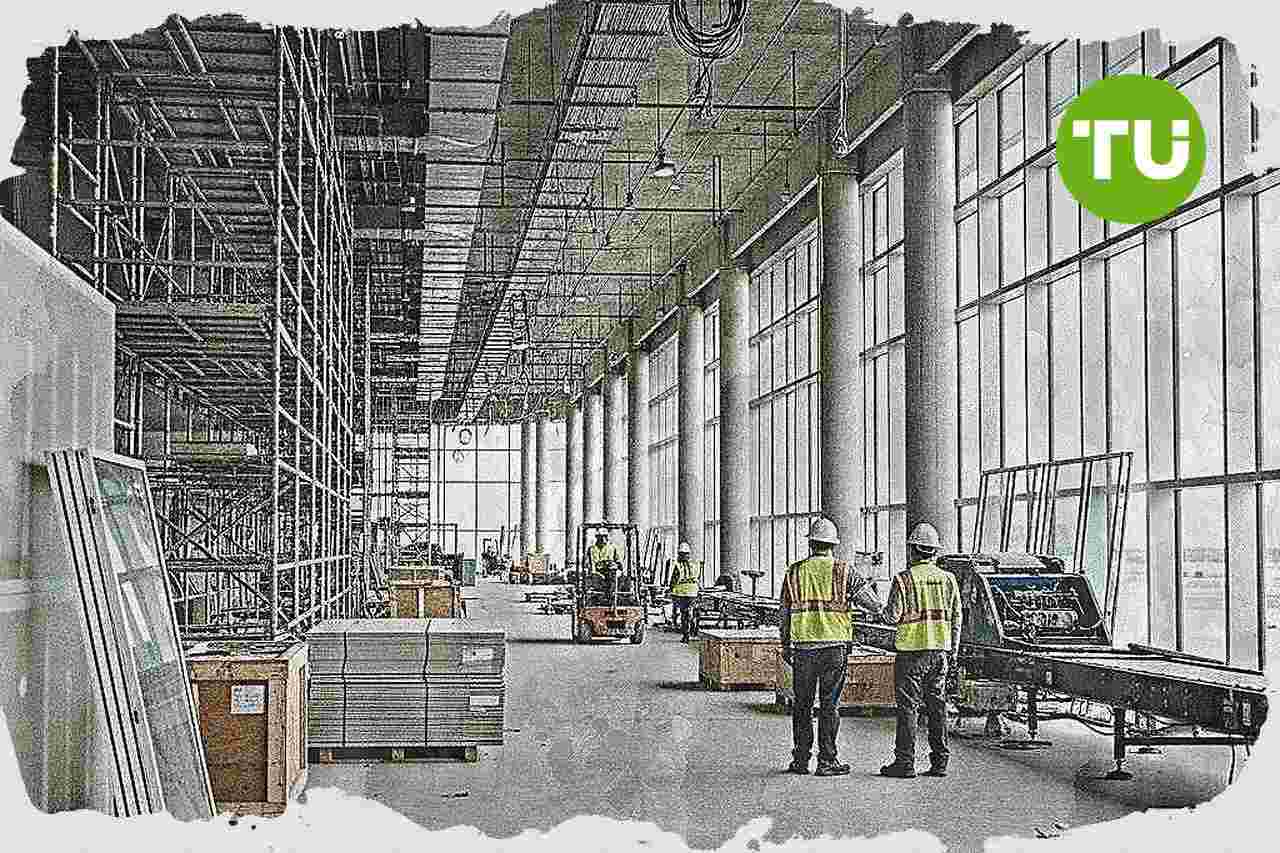
Jacksonville Aviation Authority secures a AA long-term rating with a Stable Outlook for its Series 2026 AMT revenue bonds as it advances a broader airport capital program. The assessment highlights strong liquidity and debt service coverage, while also pointing to reliance on future passenger facility charge revenue and airline agreement renewal risk.
Highlights
- KBRA assigns AA rating with Stable Outlook to Jacksonville Aviation Authority's Series 2026 AMT revenue bonds, citing strong liquidity, high debt service coverage, and expanding origin-and-destination area.
- 2026 Project is well advanced and largely de-risked, with no additional parity debt required during the five-year capital plan and substantial grant and passenger facility charge funding.
- Rating constraints include traffic concentration with top two carriers, reliance on timely approval of Applications 13 and 14 for facility charge revenue, and airline agreement renewal risk.
Credit drivers behind the 2026 bond rating
As reported by Kroll Bond Rating Agency, the AA rating on Jacksonville Aviation Authority's Series 2026 AMT revenue bonds reflects a very strong financial profile, including exceptionally high historical debt service coverage and robust liquidity. KBRA also cites a large and expanding origin-and-destination service area, supported by business, military, and tourism demand that helps sustain passenger traffic and airline service.The agency says the authority's capital program remains manageable, with the 2026 Project already well advanced and largely de-risked from a construction perspective. It also notes substantial use of grants and passenger facility charges, with no additional parity debt expected during the remaining five-year capital improvement plan.
At the same time, KBRA flags several constraints. These include traffic concentration tied to service changes among the top two carriers, volatility among some lower-cost airlines, dependence on timely approval and execution of Applications 13 and 14 for future passenger facility charge revenue, and renewal risk tied to the current airline use and lease agreement expiring within the forecast period.
Implications for funding and airport operations
For bond investors, the rating indicates that Jacksonville Aviation Authority enters the market with investment-grade backing as it finances work linked to the 2026 Project and broader airport development. The Stable Outlook suggests KBRA expects the authority to maintain credit quality if operating performance, liquidity, and project execution remain in line with expectations.KBRA says an upgrade would likely require debt service coverage to improve consistently above required minimums and above current forecast levels, alongside exceptionally strong non-airline revenue generation after the 2026 Project is completed. A downgrade could follow if the authority fails to deliver the 2026 Project and five-year capital improvement plan on time and on budget, or if a sustained drop in passenger enplanements weakens operating results, liquidity, debt metrics, or airline costs.
In our earlier coverage of KBRA’s rating view on the City of Chicago Water System, we noted that the credit profile was supported by inflation-linked rate increases, solid debt service coverage, and healthy liquidity across a large service area. The report also emphasized persistent capital needs—especially lead service line replacement—that could keep pressure on future borrowing and customer rates, alongside structural considerations tied to the second-lien bond framework.





Latest Transportation News


-
 Afghanistan
-
 Albania
-
 Algeria
-
 Angola
-
 Argentina
-
 Armenia
-
 Australia
-
 Austria
-
 Azerbaijan
-
 Bahamas
-
 Bahrain
-
 Bangladesh
-
 Belarus
-
 Belgium
-
 Bolivia
-
 Botswana
-
 Brazil
-
 Brunei
-
 Bulgaria
-
 Cambodia
-
 Cameroon
-
 Canada
-
 Chile
-
 China
-
 Colombia
-
 Congo
-
 Costa Rica
-
 Cote d'Ivoire
-
 Croatia
-
 Cuba
-
 Cyprus
-
 Czechia
-
 DR Congo
-
 Denmark
-
 Dominican Republic
-
 Ecuador
-
 Egypt
-
 El Salvador
-
 Estonia
-
 Eswatini
-
 Ethiopia
-
 Finland
-
 France
-
 Georgia
-
 Germany
-
 Ghana
-
 Greece
-
 Haiti
-
 Hong Kong
-
 Hungary
-
 India
-
 Indonesia
-
 Iran, Islamic republic
-
 Iraq
-
 Ireland
-
 Israel
-
 Italy
-
 Jamaica
-
 Japan
-
 Jordan
-
 Kazakhstan
-
 Kenya
-
 Korea
-
 Kuwait
-
 Kyrgyzstan
-
 Laos
-
 Latvia
-
 Lebanon
-
 Lesotho
-
 Libya
-
 Lithuania
-
 Luxembourg
-
 Madagascar
-
 Malaysia
-
 Malta
-
 Mauritius
-
 Mexico
-
 Moldova
-
 Mongolia
-
 Montenegro
-
 Morocco
-
 Mozambique
-
 Myanmar
-
 Namibia
-
 Nepal
-
 Netherlands
-
 New Zealand
-
 Nigeria
-
 North Macedonia
-
 Norway
-
 Oman
-
 Pakistan
-
 Palestine
-
 Panama
-
 Papua New Guinea
-
 Paraguay
-
 Peru
-
 Philippines
-
 Poland
-
 Portugal
-
 Puerto Rico
-
 Qatar
-
 Reunion
-
 Romania
-
 Rwanda
-
 Saudi Arabia
-
 Serbia
-
 Singapore
-
 Slovakia
-
 Slovenia
-
 Somalia
-
 South Africa
-
 Spain
-
 Sri Lanka
-
 Sweden
-
 Switzerland
-
 Syria
-
 Taiwan
-
 Tajikistan
-
 Tanzania
-
 Thailand
-
 Trinidad and Tobago
-
 Tunisia
-
 Turkey
-
 UAE
-
 Uganda
-
 Ukraine
-
 United Kingdom
-
United States
-
 Uruguay
-
 Uzbekistan
-
 Venezuela
-
 Vietnam
-
 Yemen
-
 Zambia
-
 Zimbabwe
- Forex
- Crypto












