

Carlyle U.S. CLO 2017-3 refinancing notes win Fitch ratings

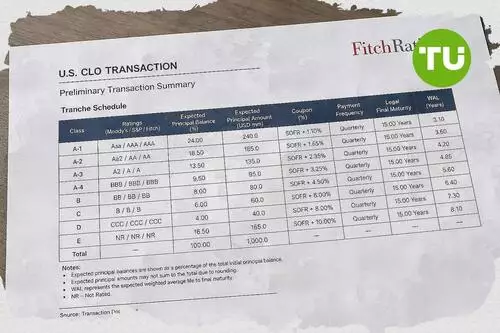
Carlyle U.S. CLO 2017-3 is completing a third refinancing of part of its debt stack while keeping the rest of its capital structure in place. The transaction will continue to finance a portfolio of about $399 million made up primarily of first-lien senior secured leveraged loans.
Highlights
- Carlyle U.S. CLO 2017-3 executed its third refinancing on Nov. 19, 2026, issuing new class X-R3 through D-1-R3 notes and maintaining Stable Outlooks on subordinated tranches.
- The $399 million CLO portfolio comprises 94.75% first-lien senior secured loans with a weighted average recovery rate of 71.93% and average credit rating of 'B'.
- As of the latest report, the deal failed its Minimum Weighted Average Coupon Test and Pay Interest Less Frequently Than Quarterly concentration limitation but passed all other collateral quality and coverage tests.
Third refinancing structure and portfolio terms
As reported by Fitch Ratings, the agency has assigned ratings and Rating Outlooks to the class X-R3 through D-1-R3 refinancing notes of Carlyle U.S. CLO 2017-3, Ltd., and has also affirmed the ratings of the existing class D-2-R2, E-R2 and F-R2 notes with Stable Outlooks.The issuer is an arbitrage cash flow collateralized loan obligation managed by Carlyle CLO Management L.L.C. The deal originally closed in August 2017, was first refinanced in March 2021 and was refinanced a second time in September 2024. On Nov. 19, 2026, the class X-R2 through D-1-R2 notes are being refinanced for a third time with net proceeds from the issuance of the new class X-R3 through D-1-R3 notes.
Together with the existing classes D-2-R2 through F-R2 and subordinated notes, the transaction will finance a portfolio of approximately $399 million. Fitch said the indicative pool has average credit quality of 'B', a weighted average rating factor of 23.54, and is composed of 94.75% first-lien senior secured loans, with a weighted average recovery rate of 71.93%.
Credit tests and broader CLO implications
The transaction carries a 2.9-year reinvestment period and reinvestment criteria that Fitch said are similar to those of other CLOs. The agency based its analysis on a stressed portfolio created by adjusting the indicative portfolio to reflect permissible concentration limits and collateral quality test levels.Fitch said 0.3% of the portfolio consists of assets rated 'CC' or below, while the portfolio balance, excluding defaults and including principal cash, stands at about $399 million. As of the latest trustee report before the refinancing date, the deal was not passing its Minimum Weighted Average Coupon Test and its Pay Interest Less Frequently Than Quarterly concentration limitation, while all other collateral quality tests, coverage tests and concentration limits were passing.
The weighted average rating of the current portfolio is 'B'. The review underscores continued investor focus on portfolio quality, covenant compliance and refinancing flexibility in the U.S. CLO market as managers seek to reset funding costs while maintaining largely senior secured loan exposure.
In a previous article, we explained the Birch Grove reset that earned Fitch final ratings for a roughly $400 million loan portfolio.






Latest Fitch Ratings News


-
 Afghanistan
-
 Albania
-
 Algeria
-
 Angola
-
 Argentina
-
 Armenia
-
 Australia
-
 Austria
-
 Azerbaijan
-
 Bahamas
-
 Bahrain
-
 Bangladesh
-
 Belarus
-
 Belgium
-
 Bolivia
-
 Botswana
-
 Brazil
-
 Brunei
-
 Bulgaria
-
 Cambodia
-
 Cameroon
-
 Canada
-
 Chile
-
 China
-
 Colombia
-
 Congo
-
 Costa Rica
-
 Cote d'Ivoire
-
 Croatia
-
 Cuba
-
 Cyprus
-
 Czechia
-
 DR Congo
-
 Denmark
-
 Dominican Republic
-
 Ecuador
-
 Egypt
-
 El Salvador
-
 Estonia
-
 Eswatini
-
 Ethiopia
-
 Finland
-
 France
-
 Georgia
-
 Germany
-
 Ghana
-
 Greece
-
 Haiti
-
 Hong Kong
-
 Hungary
-
 India
-
 Indonesia
-
 Iran, Islamic republic
-
 Iraq
-
 Ireland
-
 Israel
-
 Italy
-
 Jamaica
-
 Japan
-
 Jordan
-
 Kazakhstan
-
 Kenya
-
 Korea
-
 Kuwait
-
 Kyrgyzstan
-
 Laos
-
 Latvia
-
 Lebanon
-
 Lesotho
-
 Libya
-
 Lithuania
-
 Luxembourg
-
 Madagascar
-
 Malaysia
-
 Malta
-
 Mauritius
-
 Mexico
-
 Moldova
-
 Mongolia
-
 Montenegro
-
 Morocco
-
 Mozambique
-
 Myanmar
-
 Namibia
-
 Nepal
-
 Netherlands
-
 New Zealand
-
 Nigeria
-
 North Macedonia
-
 Norway
-
 Oman
-
 Pakistan
-
 Palestine
-
 Panama
-
 Papua New Guinea
-
 Paraguay
-
 Peru
-
 Philippines
-
 Poland
-
 Portugal
-
 Puerto Rico
-
 Qatar
-
 Reunion
-
 Romania
-
 Rwanda
-
 Saudi Arabia
-
 Serbia
-
 Singapore
-
 Slovakia
-
 Slovenia
-
 Somalia
-
 South Africa
-
 Spain
-
 Sri Lanka
-
 Sweden
-
 Switzerland
-
 Syria
-
 Taiwan
-
 Tajikistan
-
 Tanzania
-
 Thailand
-
 Trinidad and Tobago
-
 Tunisia
-
 Turkey
-
 UAE
-
 Uganda
-
 Ukraine
-
 United Kingdom
-
United States
-
 Uruguay
-
 Uzbekistan
-
 Venezuela
-
 Vietnam
-
 Yemen
-
 Zambia
-
 Zimbabwe
- Forex
- Crypto












