

KBRA sees U.S. ABS issuance reaching record levels in 2027 outlook

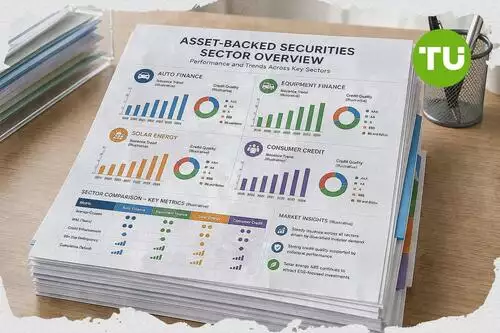
Strong consumer spending, business investment and refinancing activity are expected to push U.S. asset-backed securities issuance to a new annual high in 2027. KBRA forecasts about $392 billion of ABS issuance, up 3.2% from a projected $380 billion in 2026, while cautioning that elevated borrowing costs and changing issuer funding strategies are likely to moderate growth.
Highlights
- KBRA projects record U.S. ABS issuance in 2027, driven by 29.4% growth in data center ABS and 30.8% in whole business securitizations.
- Federal Open Market Committee forecasts for 2027 include 2.4% GDP growth, 4.1% unemployment, and 2.3% inflation, supporting consumer spending despite rate pressures.
- KBRA expects ABS credit performance and ratings to remain stable, with an ABS Stability Ratio of 95%—rising to 98% excluding solar loan ABS, which accounts for 64% of downgrades.
2027 issuance outlook and sector trends
As reported by Kroll Bond Rating Agency, its 2027 sector outlook for the U.S. asset-backed securities market points to continued expansion in overall issuance, with growth expected to vary sharply by asset class.KBRA says data center ABS and whole business securitizations are projected to post the strongest gains, rising 29.4% and 30.8%, respectively. Consumer loan, auto lease and commercial auto ABS are also expected to add to issuance growth, while prime auto loan and credit card volumes are projected to decline.
The agency says the broader economic backdrop remains supportive. Federal Open Market Committee participants project U.S. GDP growth of 2.4%, unemployment of 4.1% and inflation of 2.3% in 2027, conditions that should support consumer spending and credit demand even as higher rates continue to pressure affordability and securitization economics.
Credit performance and ratings implications
KBRA expects ABS credit performance to remain broadly stable in 2027, though differences across borrower groups and asset classes are likely to persist. It says household balance sheets remain resilient in aggregate, but that financial strength is concentrated among wealthier consumers, leaving lower-income borrowers more exposed to elevated financing costs and potential labor market weakness.Within consumer segments, prime auto and credit card performance should remain relatively stable, and recent consumer loan vintages are showing improvement. By contrast, non-prime auto and solar loan ABS are expected to stay under pressure, while commercial ABS performance is generally expected to remain stable.
Ratings stability is also expected to continue into 2027. KBRA says its ABS Stability Ratio stands at 95%, increasing to 98% when solar loan ABS is excluded, with that segment accounting for nearly 64% of downgrades, while upgrades outnumber downgrades by 3.6 times.
We recently wrote about KBRA’s Middle Market Monthly Pulse, which flagged rising defaults and surveillance downgrades in direct lending.








-
 Afghanistan
-
 Albania
-
 Algeria
-
 Angola
-
 Argentina
-
 Armenia
-
 Australia
-
 Austria
-
 Azerbaijan
-
 Bahamas
-
 Bahrain
-
 Bangladesh
-
 Belarus
-
 Belgium
-
 Bolivia
-
 Botswana
-
 Brazil
-
 Brunei
-
 Bulgaria
-
 Cambodia
-
 Cameroon
-
 Canada
-
 Chile
-
 China
-
 Colombia
-
 Congo
-
 Costa Rica
-
 Cote d'Ivoire
-
 Croatia
-
 Cuba
-
 Cyprus
-
 Czechia
-
 DR Congo
-
 Denmark
-
 Dominican Republic
-
 Ecuador
-
 Egypt
-
 El Salvador
-
 Estonia
-
 Eswatini
-
 Ethiopia
-
 Finland
-
 France
-
 Georgia
-
 Germany
-
 Ghana
-
 Greece
-
 Haiti
-
 Hong Kong
-
 Hungary
-
 India
-
 Indonesia
-
 Iran, Islamic republic
-
 Iraq
-
 Ireland
-
 Israel
-
 Italy
-
 Jamaica
-
 Japan
-
 Jordan
-
 Kazakhstan
-
 Kenya
-
 Korea
-
 Kuwait
-
 Kyrgyzstan
-
 Laos
-
 Latvia
-
 Lebanon
-
 Lesotho
-
 Libya
-
 Lithuania
-
 Luxembourg
-
 Madagascar
-
 Malaysia
-
 Malta
-
 Mauritius
-
 Mexico
-
 Moldova
-
 Mongolia
-
 Montenegro
-
 Morocco
-
 Mozambique
-
 Myanmar
-
 Namibia
-
 Nepal
-
 Netherlands
-
 New Zealand
-
 Nigeria
-
 North Macedonia
-
 Norway
-
 Oman
-
 Pakistan
-
 Palestine
-
 Panama
-
 Papua New Guinea
-
 Paraguay
-
 Peru
-
 Philippines
-
 Poland
-
 Portugal
-
 Puerto Rico
-
 Qatar
-
 Reunion
-
 Romania
-
 Rwanda
-
 Saudi Arabia
-
 Serbia
-
 Singapore
-
 Slovakia
-
 Slovenia
-
 Somalia
-
 South Africa
-
 Spain
-
 Sri Lanka
-
 Sweden
-
 Switzerland
-
 Syria
-
 Taiwan
-
 Tajikistan
-
 Tanzania
-
 Thailand
-
 Trinidad and Tobago
-
 Tunisia
-
 Turkey
-
 UAE
-
 Uganda
-
 Ukraine
-
 United Kingdom
-
United States
-
 Uruguay
-
 Uzbekistan
-
 Venezuela
-
 Vietnam
-
 Yemen
-
 Zambia
-
 Zimbabwe
- Forex
- Crypto












