

Rivian and Tesla face shifting EV demand as R2 targets mass-market SUV segment
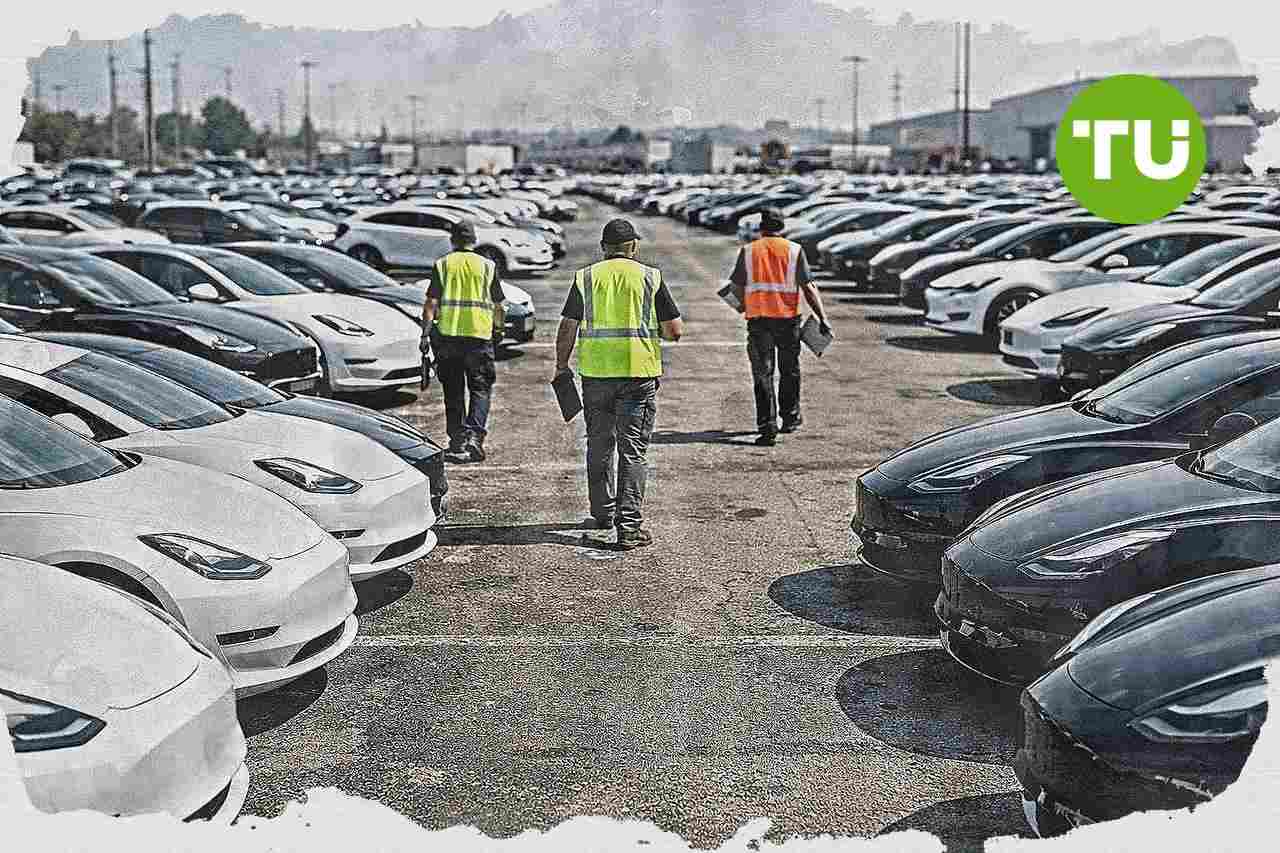
The U.S. electric vehicle market is entering a more direct mass-market contest as Rivian expands beyond premium models and Tesla shows signs of valuation pressure despite strong delivery figures. A new consumer-focused view suggests Rivian’s R2 could widen competition in the midsize SUV category that has long been led by Tesla’s Model Y.
Highlights
- Tesla delivered 480,126 vehicles in Q2, exceeding the consensus estimate of 406,600, yet the stock remained flat due to already high $1.5 trillion valuation.
- Rivian targets mass-market growth with the R2 SUV to compete directly with Tesla Model Y, entering a segment that made up 96.9% of Tesla’s 2025 sales.
- Rivian holds $4.8 billion in cash but is projected to burn $9 billion before turning cash flow positive, raising risk of dilution or debt issuance prior to 2030.
Delivery strength meets changing consumer positioning
As reported by CNBC, Tesla says it produced 451,758 vehicles and delivered 480,126 vehicles in figures reported on Thursday, July 2, well above the consensus estimate of 406,600 deliveries. Even with that outperformance, the stock does not respond strongly, reinforcing the view that positive operating news may already be reflected in a valuation of roughly $1.5 trillion, or about 15 times trailing 12-month sales.Against that backdrop, Rivian is pushing into a far broader market with the R2, a mid-market SUV aimed directly at the segment dominated by the Tesla Model Y. Tesla remains vastly larger, with a market capitalization of about $1.48 trillion versus Rivian’s $23.5 billion, and it sold nearly 1.64 million vehicles in 2025 compared with Rivian’s 42,247.
Tesla’s sales mix also highlights why Rivian’s expansion matters. The article notes that 96.9% of Tesla’s vehicle sales last year came from the Model 3 and Model Y, while the Model S, Model X and Cybertruck together accounted for only 3.1%, meaning Rivian is now moving from competing mainly with Tesla’s higher-priced niche offerings into its core volume category.
Competitive implications and funding risks
The argument for Rivian’s near-term appeal rests partly on consumer behavior rather than only on production data. The piece points to a personal purchasing indicator called the “Holly Index,” under which the author’s wife, after owning two Teslas, places a reservation for a Rivian R2 for delivery at year-end, a signal presented as evidence of shifting discretionary demand and broader appeal for the new model.That does not remove Rivian’s financial constraints. The company is not yet profitable and is seen as unlikely to reach net profitability before 2030, while its most recent quarterly report shows roughly $4.8 billion in cash on hand.
Consensus expectations cited in the article indicate Rivian may burn about $9 billion before becoming cash-flow positive. That leaves the company facing likely medium-term dilution or debt issuance, which tempers bullish sentiment even after a nearly 45% rally from its mid-May lows.
Our earlier article on Tesla’s Robotaxi launch in Miami and the Q2 delivery beat outlined how the company combined record deliveries (480,126) with progress in autonomous ride-hailing to support the long-term growth narrative. At the same time, it noted that TSLA’s price action remained technically mixed and range-bound, with traders watching key resistance levels as strong operating headlines met lingering selling pressure.






Latest Rivian Automotive News


-
 Afghanistan
-
 Albania
-
 Algeria
-
 Angola
-
 Argentina
-
 Armenia
-
 Australia
-
 Austria
-
 Azerbaijan
-
 Bahamas
-
 Bahrain
-
 Bangladesh
-
 Belarus
-
 Belgium
-
 Bolivia
-
 Botswana
-
 Brazil
-
 Brunei
-
 Bulgaria
-
 Cambodia
-
 Cameroon
-
 Canada
-
 Chile
-
 China
-
 Colombia
-
 Congo
-
 Costa Rica
-
 Cote d'Ivoire
-
 Croatia
-
 Cuba
-
 Cyprus
-
 Czechia
-
 DR Congo
-
 Denmark
-
 Dominican Republic
-
 Ecuador
-
 Egypt
-
 El Salvador
-
 Estonia
-
 Eswatini
-
 Ethiopia
-
 Finland
-
 France
-
 Georgia
-
 Germany
-
 Ghana
-
 Greece
-
 Haiti
-
 Hong Kong
-
 Hungary
-
 India
-
 Indonesia
-
 Iran, Islamic republic
-
 Iraq
-
 Ireland
-
 Israel
-
 Italy
-
 Jamaica
-
 Japan
-
 Jordan
-
 Kazakhstan
-
 Kenya
-
 Korea
-
 Kuwait
-
 Kyrgyzstan
-
 Laos
-
 Latvia
-
 Lebanon
-
 Lesotho
-
 Libya
-
 Lithuania
-
 Luxembourg
-
 Madagascar
-
 Malaysia
-
 Malta
-
 Mauritius
-
 Mexico
-
 Moldova
-
 Mongolia
-
 Montenegro
-
 Morocco
-
 Mozambique
-
 Myanmar
-
 Namibia
-
 Nepal
-
 Netherlands
-
 New Zealand
-
 Nigeria
-
 North Macedonia
-
 Norway
-
 Oman
-
 Pakistan
-
 Palestine
-
 Panama
-
 Papua New Guinea
-
 Paraguay
-
 Peru
-
 Philippines
-
 Poland
-
 Portugal
-
 Puerto Rico
-
 Qatar
-
 Reunion
-
 Romania
-
 Rwanda
-
 Saudi Arabia
-
 Serbia
-
 Singapore
-
 Slovakia
-
 Slovenia
-
 Somalia
-
 South Africa
-
 Spain
-
 Sri Lanka
-
 Sweden
-
 Switzerland
-
 Syria
-
 Taiwan
-
 Tajikistan
-
 Tanzania
-
 Thailand
-
 Trinidad and Tobago
-
 Tunisia
-
 Turkey
-
 UAE
-
 Uganda
-
 Ukraine
-
 United Kingdom
-
United States
-
 Uruguay
-
 Uzbekistan
-
 Venezuela
-
 Vietnam
-
 Yemen
-
 Zambia
-
 Zimbabwe
- Forex
- Crypto












