

Warba Bank rating affirmed at A as Fitch cites sovereign support and capital constraints

Kuwait's banking sector remains supported by strong state backing even as the economy absorbs disruption to oil revenue from the Iran conflict. Against that backdrop, Warba Bank keeps its 'A' long-term issuer rating and Stable Outlook, while its standalone credit profile continues to reflect growth, concentration risks and tight capital buffers.
Highlights
- Fitch affirms Warba Bank's Long-Term IDR at 'A' with Stable Outlook, citing strong Kuwaiti government support and government's AA-/Stable sovereign rating.
- Warba Bank's standalone profile constrained by weak capital (CET1 9.7% at end-Q3 2026), high sector exposures, and profitability below sector average at 1.5% ROA in 9M26.
- Asset quality shows modest improvement as Stage 3 financing ratio falls to 1.3% at end-Q3 2026, with high 174% loss coverage and cost of risk normalizing to 0.3%.
Rating drivers and support assumptions
As reported by Fitch Ratings, Warba Bank K.S.C.P.'s Long-Term Issuer Default Rating is affirmed at 'A' with a Stable Outlook, while its Viability Rating is affirmed at 'bb-'. The long-term rating continues to reflect potential support from the Kuwaiti authorities, as indicated by the bank's Government Support Rating of 'a', and the outlook mirrors that of Kuwait's sovereign rating at AA-/Stable.Fitch says the Kuwaiti authorities retain both the ability and willingness to support domestic banks regardless of size, franchise, funding profile or state ownership. That view is based on the government's record of backing local lenders and its interest in preserving market confidence and financial stability, given the risk of contagion across the banking system.
The agency adds that Kuwait's exceptionally strong fiscal and external balance sheets, together with the ratified public debt law, continue to support public spending and the broader economy despite severe disruption to oil revenue from the Iran conflict. Fitch expects real GDP to recover to 20.1% in 2027 from a 13% contraction in 2026, while non-oil GDP growth remains positive and bank credit growth stays at 4% to 5% in 2026 before improving to 7% to 8% in 2027 if the geopolitical environment normalizes in the first quarter of 2027.
Growth strategy, asset quality and capital impact
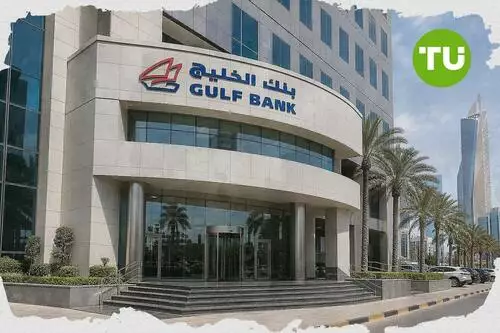
Warba Bank's standalone profile reflects what Fitch describes as a moderate but growing franchise, a weaker risk profile than peers and tight capitalization. The bank has expanded market share through organic growth and through its acquisition of about 33% of Gulf Bank K.S.C.P., a move that Fitch says could lead to Kuwait's third-largest bank if broader M&A plans succeed, although no transaction timeline or further details are disclosed.Fitch says the bank's Islamic business model is corporate-oriented, contributing to high concentrations. Its risk profile remains shaped by above-sector growth, exposure to real estate and construction at 35% of financing at end-first half 2026, financing for securities purchases at 11%, and high single-obligor concentrations, with the top 20 exposures equal to 2.7 times common equity Tier 1. The agency says underwriting standards and controls have strengthened, but the financing book remains relatively unseasoned and market risk is elevated by a large equity and investment portfolio.
Asset quality metrics improve modestly, with the Stage 3 financing ratio at 1.3% at end-third quarter 2026 from 1.4% at end-2025, and the Stage 2 ratio at 5.9% from 7.2%, helped by financing growth, recoveries and write-offs. Total loss allowance coverage of Stage 3 financing remains high at 174%, and Fitch expects the Stage 3 ratio to stay around 1.4% through 2027, while cost of risk normalizes to about 0.3% after a higher non-recurring charge in the first nine months of 2026.
Profitability stays below the sector average, with operating profit to risk-weighted assets at 1.5% in 9M26 on an annualized basis versus 1.6% in 2025, reflecting a thin net financing margin of 1.3%, a cost-to-income ratio of 48% and a rising contribution from equity-accounted associate income. Fitch expects operating profit to risk-weighted assets at 1.5% to 1.7% through 2027 as financing and fee income grow and impairment charges normalize.
Capital remains a key constraint, with the CET1 ratio at 9.7% at end-third quarter 2026, or 10.4% including interim profits net of expected dividends, against a regulatory minimum of 9.5%. Fitch says this is the lowest among rated Kuwaiti banks and leaves only a limited buffer over regulatory requirements, although the agency expects CET1 to recover toward 11% to 11.5% by 2028 through earnings retention. Funding is still led by customer deposits, which account for 85% of total funding, while liquidity remains adequate despite concentrated deposits, supported by central bank facilities and access to the domestic sukuk market.
In a previous article, we explained Kuwait Finance House’s rating upgrade to A+ as Fitch cited parent support expectations.






Latest Fitch Ratings News


-
 Afghanistan
-
 Albania
-
 Algeria
-
 Angola
-
 Argentina
-
 Armenia
-
 Australia
-
 Austria
-
 Azerbaijan
-
 Bahamas
-
 Bahrain
-
 Bangladesh
-
 Belarus
-
 Belgium
-
 Bolivia
-
 Botswana
-
 Brazil
-
 Brunei
-
 Bulgaria
-
 Cambodia
-
 Cameroon
-
 Canada
-
 Chile
-
 China
-
 Colombia
-
 Congo
-
 Costa Rica
-
 Cote d'Ivoire
-
 Croatia
-
 Cuba
-
 Cyprus
-
 Czechia
-
 DR Congo
-
 Denmark
-
 Dominican Republic
-
 Ecuador
-
 Egypt
-
 El Salvador
-
 Estonia
-
 Eswatini
-
 Ethiopia
-
 Finland
-
 France
-
 Georgia
-
 Germany
-
 Ghana
-
 Greece
-
 Haiti
-
 Hong Kong
-
 Hungary
-
 India
-
 Indonesia
-
 Iran, Islamic republic
-
 Iraq
-
 Ireland
-
 Israel
-
 Italy
-
 Jamaica
-
 Japan
-
 Jordan
-
 Kazakhstan
-
 Kenya
-
 Korea
-
 Kuwait
-
 Kyrgyzstan
-
 Laos
-
 Latvia
-
 Lebanon
-
 Lesotho
-
 Libya
-
 Lithuania
-
 Luxembourg
-
 Madagascar
-
 Malaysia
-
 Malta
-
 Mauritius
-
 Mexico
-
 Moldova
-
 Mongolia
-
 Montenegro
-
 Morocco
-
 Mozambique
-
 Myanmar
-
 Namibia
-
 Nepal
-
 Netherlands
-
 New Zealand
-
 Nigeria
-
 North Macedonia
-
 Norway
-
 Oman
-
 Pakistan
-
 Palestine
-
 Panama
-
 Papua New Guinea
-
 Paraguay
-
 Peru
-
 Philippines
-
 Poland
-
 Portugal
-
 Puerto Rico
-
 Qatar
-
 Reunion
-
 Romania
-
 Rwanda
-
 Saudi Arabia
-
 Serbia
-
 Singapore
-
 Slovakia
-
 Slovenia
-
 Somalia
-
 South Africa
-
 Spain
-
 Sri Lanka
-
 Sweden
-
 Switzerland
-
 Syria
-
 Taiwan
-
 Tajikistan
-
 Tanzania
-
 Thailand
-
 Trinidad and Tobago
-
 Tunisia
-
 Turkey
-
 UAE
-
 Uganda
-
 Ukraine
-
 United Kingdom
-
United States
-
 Uruguay
-
 Uzbekistan
-
 Venezuela
-
 Vietnam
-
 Yemen
-
 Zambia
-
 Zimbabwe
- Forex
- Crypto












