

American Express shares fall nearly 4% as network volume misses and selling pressure persists

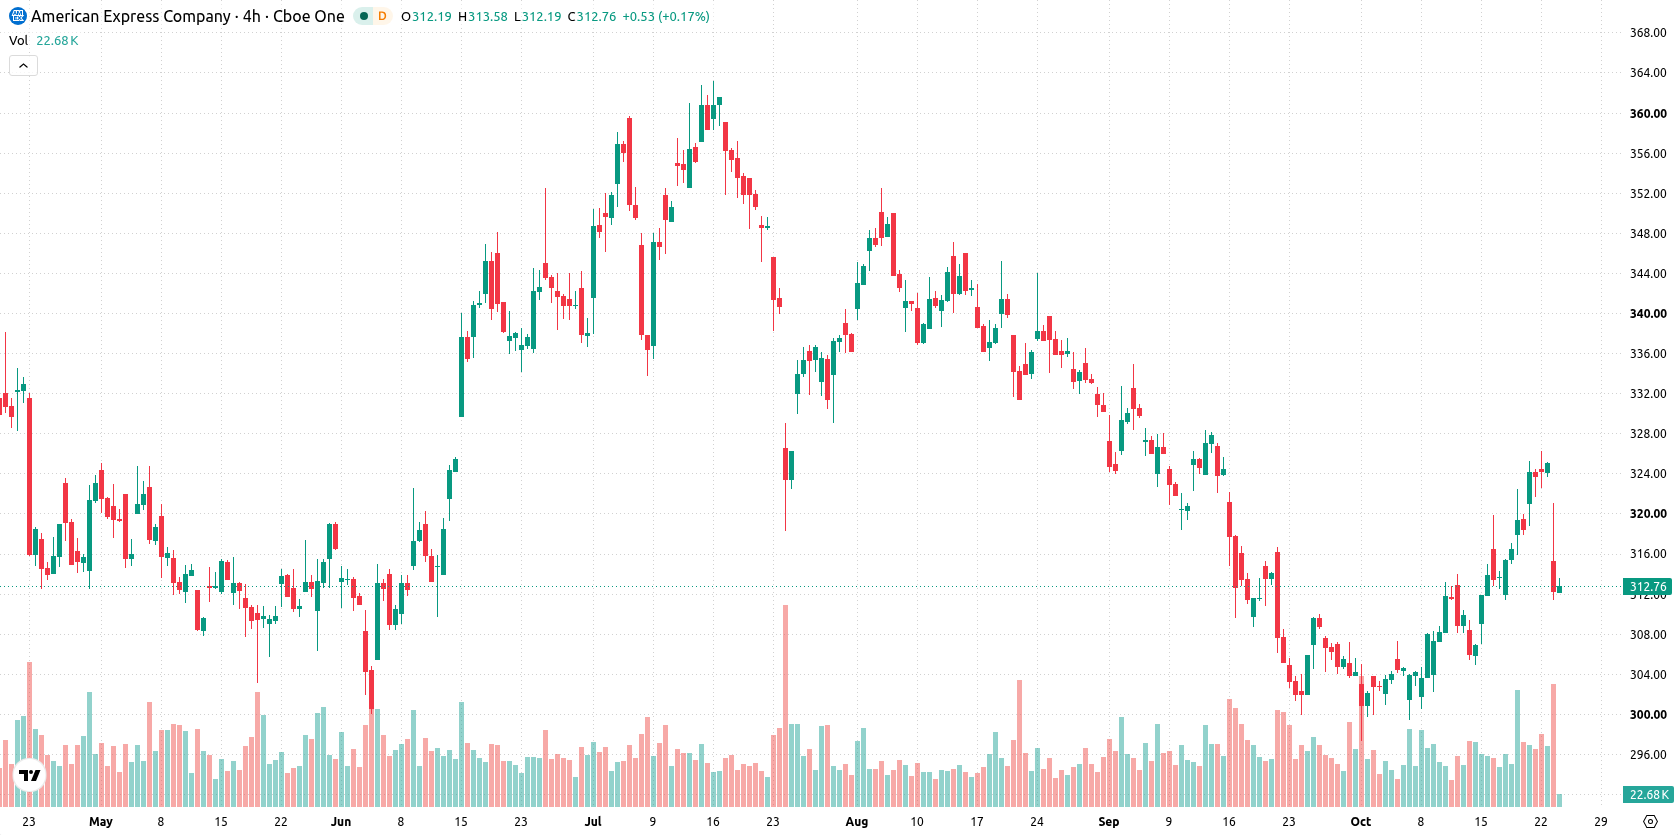
American Express Company (AXP) dropped 3.64% following a downside gap after its quarterly network volume missed Wall Street estimates, even as its Q3 2026 earnings surpassed expectations and guidance was raised. The move is supported by continued bearish signals, with the stock trading above only its MA-20 and remaining below both medium- and long-term averages.
 326.49
Highlights
- American Express posted Q3 2026 earnings of $4.68 per share on revenue of $20.06 billion, surpassing analyst forecasts.
- Guidance for 2026 earnings per share was raised, with plans for a 5% workforce reduction and a $0.95 dividend declared.
- Shares of American Express fell 3.64% to $313.32 with short-term technicals mixed, and a forecasted range of $301.57 to $320.78 for the next five trading days.
Raised outlook offset by workforce cuts and persistent selling pressure
American Express reported Q3 2026 earnings of $4.68 per share, exceeding analyst expectations on revenue of $20.06 billion, driven by higher card spending. The company raised its 2026 earnings per share guidance and kept its revenue outlook unchanged. Increased customer engagement costs and network volume falling short of estimates were reported, along with a 5% reduction in global workforce and the declaration of a $0.95 per share quarterly dividend. These developments occurred as price action has remained under broader selling pressure.
Short-term resilience limited as long-term averages cap upside
AXP is currently trading above its MA-20 level of $309.85, but remains below the MA-50 at $319.8 and the MA-200 at $327.63. This technical setup signals recent short-term strength, yet highlights medium- and longer-term weakness. Nearest resistance stands at $313.33, with immediate support found at $311.79. The overall trend remains bearish, as the longer-term moving averages cap sustained upside.
Earlier, analysts noted that American Express was exhibiting ongoing negative momentum amid mixed financial results and workforce restructuring. The latest quarterly data reinforces this cautious outlook, with heightened attention now warranted on whether the stock can sustain support above $301.57 or risk renewed downside if bearish trends persist.






Latest American Express News


-
 Afghanistan
-
 Albania
-
 Algeria
-
 Angola
-
 Argentina
-
 Armenia
-
 Australia
-
 Austria
-
 Azerbaijan
-
 Bahamas
-
 Bahrain
-
 Bangladesh
-
 Belarus
-
 Belgium
-
 Bolivia
-
 Botswana
-
 Brazil
-
 Brunei
-
 Bulgaria
-
 Cambodia
-
 Cameroon
-
 Canada
-
 Chile
-
 China
-
 Colombia
-
 Congo
-
 Costa Rica
-
 Cote d'Ivoire
-
 Croatia
-
 Cuba
-
 Cyprus
-
 Czechia
-
 DR Congo
-
 Denmark
-
 Dominican Republic
-
 Ecuador
-
 Egypt
-
 El Salvador
-
 Estonia
-
 Eswatini
-
 Ethiopia
-
 Finland
-
 France
-
 Georgia
-
 Germany
-
 Ghana
-
 Greece
-
 Haiti
-
 Hong Kong
-
 Hungary
-
 India
-
 Indonesia
-
 Iran, Islamic republic
-
 Iraq
-
 Ireland
-
 Israel
-
 Italy
-
 Jamaica
-
 Japan
-
 Jordan
-
 Kazakhstan
-
 Kenya
-
 Korea
-
 Kuwait
-
 Kyrgyzstan
-
 Laos
-
 Latvia
-
 Lebanon
-
 Lesotho
-
 Libya
-
 Lithuania
-
 Luxembourg
-
 Madagascar
-
 Malaysia
-
 Malta
-
 Mauritius
-
 Mexico
-
 Moldova
-
 Mongolia
-
 Montenegro
-
 Morocco
-
 Mozambique
-
 Myanmar
-
 Namibia
-
 Nepal
-
 Netherlands
-
 New Zealand
-
 Nigeria
-
 North Macedonia
-
 Norway
-
 Oman
-
 Pakistan
-
 Palestine
-
 Panama
-
 Papua New Guinea
-
 Paraguay
-
 Peru
-
 Philippines
-
 Poland
-
 Portugal
-
 Puerto Rico
-
 Qatar
-
 Reunion
-
 Romania
-
 Rwanda
-
 Saudi Arabia
-
 Serbia
-
 Singapore
-
 Slovakia
-
 Slovenia
-
 Somalia
-
 South Africa
-
 Spain
-
 Sri Lanka
-
 Sweden
-
 Switzerland
-
 Syria
-
 Taiwan
-
 Tajikistan
-
 Tanzania
-
 Thailand
-
 Trinidad and Tobago
-
 Tunisia
-
 Turkey
-
 UAE
-
 Uganda
-
 Ukraine
-
 United Kingdom
-
United States
-
 Uruguay
-
 Uzbekistan
-
 Venezuela
-
 Vietnam
-
 Yemen
-
 Zambia
-
 Zimbabwe
- Forex
- Crypto












