

The Methodist Hospitals outlook revised to stable as Fitch affirms 'BBB-' ratings
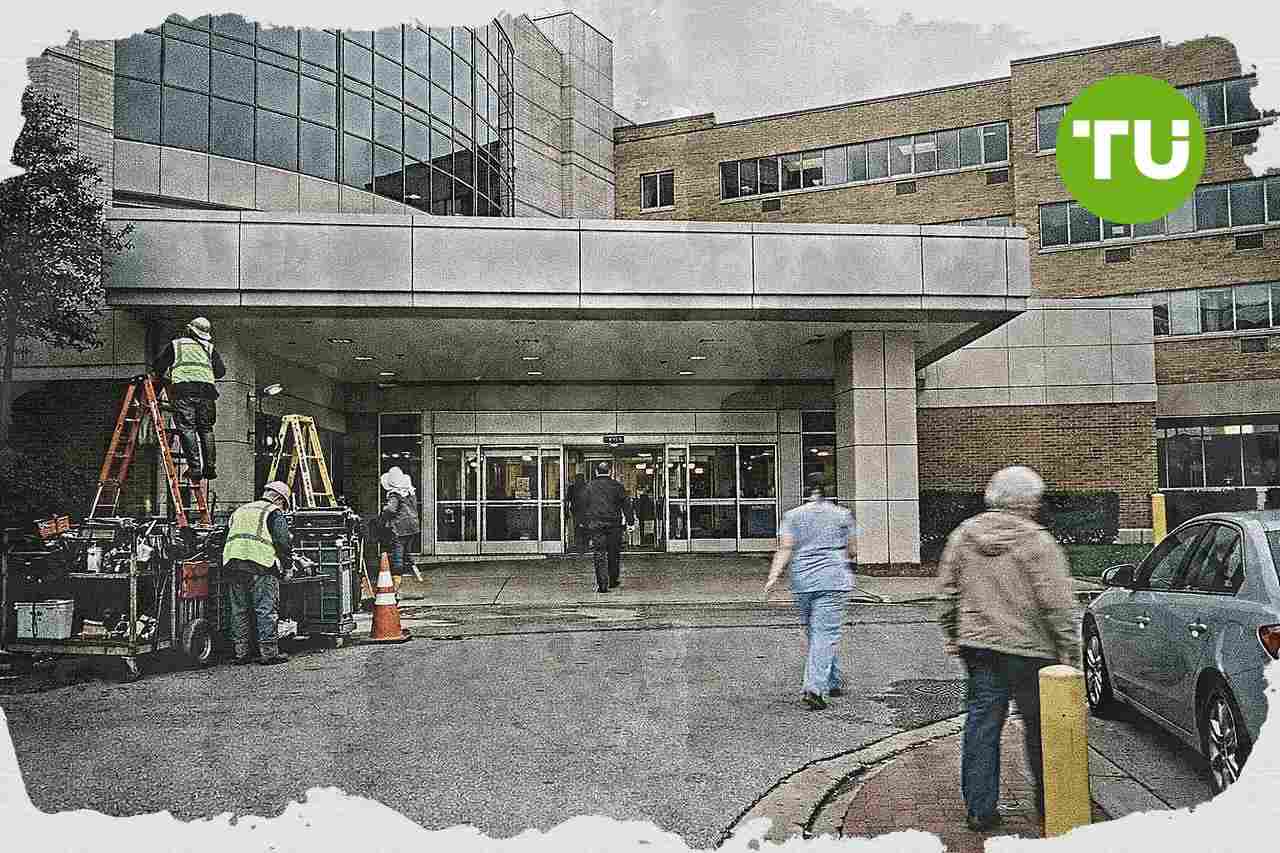
Northwest Indiana safety-net provider The Methodist Hospitals is seeing a more stable credit outlook as stronger supplemental Medicaid funding supports its financial recovery. Fitch Ratings affirms the hospital's Issuer Default Rating and outstanding revenue bonds at 'BBB-' while citing low debt and supportive liquidity despite continued operating pressures.
Highlights
- Fitch revised Methodist Hospitals' outlook to Stable from Negative and affirmed its 'BBB-' ratings due to improved supplemental DSH payments and expectations of sustained funding.
- Methodist's operating recovery remains uneven despite early fiscal 2026 results ahead of budget, with persistent weak revenue defensibility and challenging government-heavy payor mix.
- Rating stability depends on gradual operating improvements and liquidity, with downgrade risk if EBITDA margins remain below 4% and limited upgrade potential without margins above 6% and strong balance sheet.
Rating action tied to stronger DSH support
As reported by Fitch Ratings, the outlook revision to Stable from Negative reflects recently improved supplemental Disproportionate Share Hospital, DSH, payments and the agency's expectation that this funding stream will remain stronger going forward. Fitch says Methodist's 'BBB-' rating balances a low debt burden and adequate financial flexibility against weak operating risk and a challenging government-heavy payor mix.The ratings apply to Methodist's Issuer Default Rating and outstanding revenue bonds, which are secured by a pledge of gross revenue and a debt service reserve fund. Fitch says the hospital remains exposed to changes in supplemental funding, although management indicates that federal and state remedies tied to Section 203-related disruptions no longer exist because of legislative changes.
Methodist continues to have weak revenue defensibility, according to Fitch, because it operates as a safety-net provider in northwest Indiana with mixed service area demographics and a heavy share of government payors. At the same time, the agency notes that the system benefits from a leading local market position that supports its role as an important regional healthcare provider.
Operational recovery remains uneven
Fitch continues to assess Methodist's operating risk as weak even after better fiscal 2025 results. Revenue growth and higher Medicaid DSH revenue reduce the operating loss from fiscal 2024, and Fitch views earlier supplemental payment disruptions as the main driver of the prior deterioration in operating performance.Management's turnaround plan includes payer actions, revenue cycle improvements, labor and supply-chain efficiencies, and growth in key service lines supported by its relationship with the University of Chicago. Early fiscal 2026 results are ahead of budget, but softer emergency department and outpatient trends indicate that the recovery remains uneven.
Fitch says Methodist's financial profile remains consistent with a midrange 'bbb' assessment because debt is low and cash and investments remain supportive. The hospital returns to compliance with its master trust indenture debt service covenant in 2025, while high capital needs remain a secondary constraint as management focuses on maintenance and equipment upgrades without undermining liquidity.
In Fitch's base case, rating stability depends on gradual operating improvement with liquidity remaining supportive of the current rating. The agency says downside pressure could emerge from significant balance sheet deterioration or failure to sustain operating improvement, particularly if operating EBITDA margins are expected to stay below 4% over the long term, while an upgrade is unlikely during the outlook period unless margins are sustained at 6% or higher alongside continued balance sheet strength.
Our earlier coverage of Illinois’ Build Illinois Bonds explained how the rating was supported by an irrevocable state appropriation and a broad pledge of sales-tax revenues, alongside strong debt service coverage and limits on additional borrowing. We also noted that although sales-tax collections have been relatively steady, they remain economically sensitive, which is a key consideration for investors ahead of Illinois’ planned 2026 issuance.





Latest Reporting News



-
 Afghanistan
-
 Albania
-
 Algeria
-
 Angola
-
 Argentina
-
 Armenia
-
 Australia
-
 Austria
-
 Azerbaijan
-
 Bahamas
-
 Bahrain
-
 Bangladesh
-
 Belarus
-
 Belgium
-
 Bolivia
-
 Botswana
-
 Brazil
-
 Brunei
-
 Bulgaria
-
 Cambodia
-
 Cameroon
-
 Canada
-
 Chile
-
 China
-
 Colombia
-
 Congo
-
 Costa Rica
-
 Cote d'Ivoire
-
 Croatia
-
 Cuba
-
 Cyprus
-
 Czechia
-
 DR Congo
-
 Denmark
-
 Dominican Republic
-
 Ecuador
-
 Egypt
-
 El Salvador
-
 Estonia
-
 Eswatini
-
 Ethiopia
-
 Finland
-
 France
-
 Georgia
-
 Germany
-
 Ghana
-
 Greece
-
 Haiti
-
 Hong Kong
-
 Hungary
-
 India
-
 Indonesia
-
 Iran, Islamic republic
-
 Iraq
-
 Ireland
-
 Israel
-
 Italy
-
 Jamaica
-
 Japan
-
 Jordan
-
 Kazakhstan
-
 Kenya
-
 Korea
-
 Kuwait
-
 Kyrgyzstan
-
 Laos
-
 Latvia
-
 Lebanon
-
 Lesotho
-
 Libya
-
 Lithuania
-
 Luxembourg
-
 Madagascar
-
 Malaysia
-
 Malta
-
 Mauritius
-
 Mexico
-
 Moldova
-
 Mongolia
-
 Montenegro
-
 Morocco
-
 Mozambique
-
 Myanmar
-
 Namibia
-
 Nepal
-
 Netherlands
-
 New Zealand
-
 Nigeria
-
 North Macedonia
-
 Norway
-
 Oman
-
 Pakistan
-
 Palestine
-
 Panama
-
 Papua New Guinea
-
 Paraguay
-
 Peru
-
 Philippines
-
 Poland
-
 Portugal
-
 Puerto Rico
-
 Qatar
-
 Reunion
-
 Romania
-
 Rwanda
-
 Saudi Arabia
-
 Serbia
-
 Singapore
-
 Slovakia
-
 Slovenia
-
 Somalia
-
 South Africa
-
 Spain
-
 Sri Lanka
-
 Sweden
-
 Switzerland
-
 Syria
-
 Taiwan
-
 Tajikistan
-
 Tanzania
-
 Thailand
-
 Trinidad and Tobago
-
 Tunisia
-
 Turkey
-
 UAE
-
 Uganda
-
 Ukraine
-
 United Kingdom
-
United States
-
 Uruguay
-
 Uzbekistan
-
 Venezuela
-
 Vietnam
-
 Yemen
-
 Zambia
-
 Zimbabwe
- Forex
- Crypto












